›

If you run a company in Canada, life insurance is not just a part of personal planning. Business life insurance can help a business owner protect money that comes in, pay off debts, and keep future plans on track. It also helps the people who count on the company. This is true if you are part of a family business, work with partners, or if your business is set up as a company.
The best insurance policy for you will depend on how your business is set up, what risks you face, and how much you have to spend. So, it is a good idea to compare a few options before you pick your coverage.
A sudden loss can put a lot of pressure on a business owner. Business life insurance helps when cash flow is low, loans need to be paid back, or when changes in leaders make clients and lenders worry.
This type of insurance can protect both family members and business interests at the same time. What the insurance policy offers depends on which one you choose. Life insurance proceeds or the cash value can help keep things running, pass ownership to someone else, or help with long-term planning. The next sections talk about where this protection from life insurance, cash value, and insurance proceeds is most important for a business owner.
Many owners mix business risk with personal risk. If you have guaranteed loans or use your savings for the company, a loss can hurt more than the office. If you depend on business income at home, that risk grows. That is why life insurance is important.
A death benefit can help family members. It may replace income and take pressure off personal assets. It keeps cash flow steady and gives your family time while legal and business things get figured out. Sometimes, both personal life insurance and business coverage help.
This is a main benefit for small business owners in Canada. You protect the company and help your family. They will not have to make rushed choices, sell fast, or take on more debt in a hard time.
Now think about the people who work in the business. If a business owner dies, the partner who is still there could face big problems like debt, not enough staff, and even extra pressure from clients or suppliers. These problems can hurt business continuity fast.
Insurance proceeds can give quick cash when it is really needed. A business owner may use this money to get someone to run things for a while, pay urgent bills, or help with the change to a new owner. This is how succession planning moves from just talk into real action.
For business partners, the idea is clear. This coverage can help the surviving partner keep control, stop chaos, and stick to the plan already made in the shareholder or partnership agreement. This will help the team feel steady and keep the business strong when a new person takes charge.
Business life insurance is not just one type of plan. It means different ways to use a life insurance policy. This can help protect business loans, owners, key people, and future plans for who will own the company.
For Canadian corporations, the company can have the coverage. If the insured person dies, the company gets the insurance proceeds. These funds can help pay back business loans, handle buyouts, or cover other needs for running the business. The setup depends on the size of company debt, who owns the business, and which people the business needs the most.
Lenders want things to keep running as normal. When a founder or guarantor dies, the bank may look at the loan rules again or ask for the money back. This is why the owners use life insurance for help with debts.
A life insurance policy can give money to protect the cash flow. It stops you from having to sell what you own in a short time. Sometimes, key person insurance helps too. Lenders may want one top leader or owner to stay at the business.
It may help you pay for:
You can use this kind of planning with business overhead insurance Canada or business overhead expense insurance. It gives you better risk protection.
Sometimes in a company, it is not just the owner who is the biggest risk. It can be a specialist. What is key person insurance? It is a way for a business to protect itself if a person who brings in a lot of revenue, has special technical skills, or shows strong leadership dies.
The death benefit can give the business some time. The company can use this time to find, hire, and train someone new. It can also help calm lenders and help steady the business. If you are a business owner, key person protection could be even more important than you think. This is true when teams are small or work closely together.
People often make these mistakes:
There are different types of life insurance to help in business planning. In Canada, the main options are term life, whole life, and universal life. Each type fits different goals and time frames.
Term life insurance works well for short-term needs. These needs can be things like paying off debt or handling short deals. Whole life and universal life are permanent plans. These plans are better for long-term goals.
Businesses can use life insurance in other ways too. Corporate-owned life insurance and key person insurance use these different types of policies for business needs.
Yes, business life insurance can help protect companies in Canada if a key employee passes away. Key person insurance is often bought when that person is important for sales, daily work, customer trust, or technical skill.
If the key employee dies, the death benefit can help keep the business running. The company might use it to cover hiring and training costs, pay debts, or help find new leaders. This is useful for founders, executives, and other key employees.
Both term and permanent life insurance can be options for the company. A small business may pick term life insurance since it costs less. A bigger or more steady company might go for permanent life insurance when it wants lasting coverage and more cash value.
Keywords: life insurance, death benefit, permanent life, business continuity, person insurance, key person insurance, permanent life insurance, term life, business life insurance, term life insurance, key employees
Corporate-owned life insurance means the company owns the insurance policy. The business pays premiums using corporate dollars. If the insured person dies, the company gets the death benefit. This setup is often used by owners of businesses that are incorporated.
One reason people look at this option is for tax efficiency. If the life insurance is set up right, the corporation usually gets the death benefit tax free. Some of that money may also go into the capital dividend account. This can help make tax-friendly payments to shareholders.
Permanent insurance plans can also grow cash value inside the policy. For many businesses in Canada, corporate owned life insurance supports liquidity, succession planning, and keeps the balance sheet strong over time. The tax treatment here can be tricky. So, make sure to talk with a licensed advisor, an accountant, or a lawyer before you decide.
Ownership changes can be tough if there is no money to work with. Business life insurance gives shareholders and partners a simple way to be ready for this time. It offers money when someone dies.
A life insurance payout may help buy shares from an estate. It may also help with succession planning. It can lower the chance of any problems over fair market value. Because of this, many small companies use shareholder life insurance, partner life insurance, and other agreements.
A buy-sell agreement lays out what happens to a share of the business when one owner dies. The hard part is getting the funds to buy out that share. That is why many people in Canada turn to buy sell life insurance Canada or buy sell agreement insurance Canada.
Insurance proceeds give the surviving owners money to buy the share of the business from the family or estate of the deceased owner. This helps avoid delays, cuts the need to borrow, and supports a smooth deal at fair market value.
If you wonder, how does buy sell insurance work, here is what it does: it provides the cash to handle the purchase set in the agreement. When it comes to business succession insurance Canada, it is one of the most practical tools for the job.
Partner protection plans are made to help with the ownership risk in a business. If one person dies, the people or company left may need money to cover the share of the business that is lost.
A shareholder agreement usually tells who should get the money. Sometimes, the company gets it. Other times, an owner may be named based on the way the business is set up. The answer depends on the agreement, ownership, and the reason for the policy.
In Canada, partnership life insurance and shareholder protection insurance often use term life or term life insurance if the need is short. Permanent life insurance may be used for longer plans. Make sure to check who the beneficiary is with a lawyer and someone who knows taxes before you apply.
Not every company will need the same setup. But, small business life insurance in Canada is something to think about if you are a business owner and have debt, people who depend on you, partners, or key employees. It is also important if you want to pass your company on to others one day.
This can be right for many people like incorporated professionals, consultants, founders, contractors, and family-run businesses. If a small business really relies on one or two people, owns business assets, or needs to give stability to lenders and family, you may want to look at business life insurance and compare your options.
Incorporated professionals often keep their earnings in the company. That means life insurance can be a big topic when talking about how to protect business assets, plan for business continuity, and look after family needs.
The insurance policy can be owned by the person or by the corporation. Each choice leads to different tax treatment, ways of handling the policy, and what you can do with the money later. There is not one simple answer that works for every doctor, lawyer, consultant, or other incorporated professional.
If you are asking who should be the beneficiary, the answer depends on what you want. For business continuity, the corporation may be the beneficiary. A family member may be named if you want personal protection. It is good to talk this over with a business insurance advisor Canada, an accountant, and a lawyer before making a decision.
For many founders and contractors, the business can depend on one person. If that person is not there, it can hit the company hard. Money coming in can go down fast. This is why it is important to think about insurance, even for a small business.
The main benefits are practical. Coverage can help cash flow stay steady. It can give support to family income. It can make lenders feel safe and help the business get through changes. This is often the reason people talk about business insurance for entrepreneurs Canada when they make plans.
You may look at affordable business insurance Canada and compare it with choices like business continuation insurance Canada, executive life insurance Canada, and commercial life insurance Canada. You can ask a licensed advisor or use a platform like Policy Ninja to compare life insurance Canada and not feel stressed.
How much life insurance your business needs depends on what you want to protect. The amount of coverage is often linked to what you owe, ownership needs, and the value a person adds to the business.
A life insurance policy might need to cover loans, buyout needs, or business assets tied to succession planning. There is no set number for every business. Start by looking at risk, budget, agreements, and replacement costs. Then compare insurance policy options for what is best.
A smart risk assessment looks at more than income. You may need to measure debt, buyout obligations, lender demands, and the fair market value of an owner’s interest. That helps shape the amount of coverage.
Permanent plans may also build cash value, which can matter for long-term goals. Term plans may fit short obligations better. Your insurance policy should match the reason you are buying it.
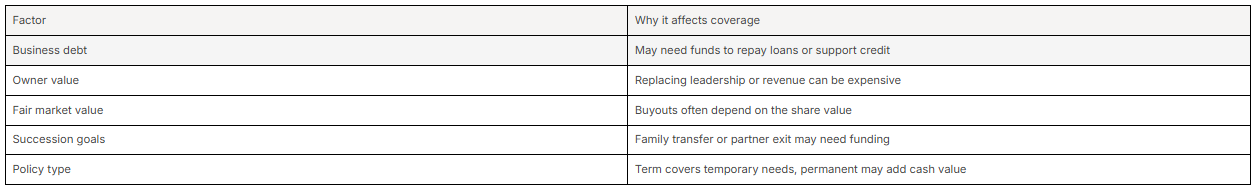
Start by going over things in a simple way. Look at the debts. Which ones will be left? If you die, will your partner need to buy out your share of the business? Will your family members end up owning part of the company without enough money to cover their needs? These are big questions in succession planning for any business owner.
Next, think about fair market value and planning for the estate. If the business will stay with the family or go to surviving owners, it is not just about the legal papers. Getting the right funding is just as important. Insurance can help give that money when needed.
Before you apply, ask yourself: who needs to be protected, who will own the policy, who should get the payout, what timeline is needed, and can your budget handle permanent or term coverage? It is good for each business owner to talk first with a licensed advisor, accountant, and lawyer about estate planning, fair market value, all family members, and surviving owners.
To sum up, having the right business life insurance in Canada helps you protect your company. It also takes care of your family and your business partners. There are many choices, like key person insurance, corporate-owned plans, and buy-sell deals. It is important for you to know your own needs so you can pick what works best for you. If you are a Canadian business owner, look at how much coverage you need. Think about your debts, risks, and who will run the business next. Every business has its own needs for life insurance. Take some time to check your options and get a quote with PolicyNinja. Your peace of mind is there, waiting for you.
Corporate-owned life insurance may offer some tax advantages. The death benefit is usually paid out tax free to the corporation. Depending on the policy’s adjusted cost basis, some of the amount may count as capital dividend account room. With permanent coverage, the policy may also build up cash value and have good tax treatment inside the policy.
Personal life insurance is made to help your family or your own stuff if something happens to you. Business life insurance helps protect a company. It helps with things the company has to pay for or can help protect the business owner or key people. If you are a business owner, the death benefit can go to the company or someone else you choose. It depends on how you set up the life insurance policy.
The person who gets the money from the life insurance policy depends on what the company needs the policy for. Sometimes, the company takes the spot as the beneficiary because it needs help with debts, key person coverage, or money for a buyout. In some cases, the owner or their estate is the one named to get the money. The business owner should pick the right beneficiary to match the fair market value and any agreements.
Cindy David, CFP, CLU, FEA, TEP, is President & Estate Planning Advisor at Cindy David Financial Group Ltd. in Vancouver. A recognized leader in wealth management and estate planning, Cindy guides clients with strategic, tax-effective solutions while championing innovation and women’s leadership in the financial industry. She is the former Chair of the Conference for Advanced Life Underwriting (CALU) — Canada’s professional association for senior life insurance and financial advisors that advances education, advocacy, and best practices in advanced planning and public policy.


