›

Commercial life insurance in Canada is important. Your company might rely on you more than you know. If you own a business, run a small shop, work as a contractor, or share ownership with others, the right life insurance policy can help. It may cover your work, debts, and plans for the future.
Commercial life insurance is often a mix of business insurance plans. It can help your company keep going if key people leave, help with loans, protect partners, or support your long-term plans. The best plan for you depends on your specific situation.
For a business owner in Canada, risk can hurt you and your business. If a key person gets sick or dies, it can hurt your cash flow and business continuity right away. This can be bad for your staff, your family, the lenders, and your clients.
Life insurance is a safety net. It can keep your bills paid, help with changes in who owns the business, and protect the value of what you have made. That is why many business owners look at life insurance before a crisis. They know it is better to be ready with life insurance than try to deal with big changes after something happens to a key person.
Small business owners often manage many tasks at the same time. You may need to make sales, lead your team, sign for loans, and support your home with your business income. If problems happen, money troubles can hit both your company and your personal income.
Big companies also face risk. Someone like a founder, leader, or shareholder can be tough to replace. Serious illness or death can hurt cash flow, debt repayment, and how the team makes choices.
Common issues include:
A strong business legacy needs you to have a plan for change. Life insurance can give money when it is needed most. It helps those left behind cover what they owe, so they do not have to rush into bad choices. This supports business continuity during what can be a tough time.
Life insurance also does a lot in succession planning. The death benefit can help with passing the business to family, partners, shareholders, or maybe to a new buyer. The type of insurance you pick should fit if you want short-term protection or support your legacy over the long term.
Some owners get term coverage for their temporary needs. Others want lifetime coverage and pick permanent life insurance, which can also grow in cash value. When you use business succession insurance Canada the right way, you help keep good relationships, steady ownership, and protect all your years of work.
Commercial life insurance in Canada can help with more than one issue. It can help pay off loans, support a business partner in a buyout, cover lost income, or give cash when there is a change in ownership. Most of the time, it is something you use for planning, not just one type of product.
Many owners mix life insurance coverage with others, like disability insurance or critical illness insurance. This mix lets people deal with risk if they die, get sick, or need time away from work. The following parts show what it can protect for you.
Your business often helps more people than you might notice. Your family needs your pay. The key employees depend on steady paychecks. A business partner counts on you for planning, sales, or running things. There is one insurance policy that can cut down problems for all these groups.
When the company has coverage on a key person, the death benefit can give the company some space to handle things. It can help the business keep going while leaders work on what to do next.
That support can include:
Borrowing money can help a business grow. But debt puts pressure on the company. If an owner or guarantor dies, the lender will want answers fast about how the money will be paid back. This can be tough when the business is dealing with the shock and changes.
Business loan protection insurance can help with that risk. Sometimes, this insurance is used to help pay the debt so the company does not have to sell its stuff or cut back on its work. This is one reason why a lender may ask about business insurance when you get financing.
Some business owners use permanent insurance with cash value as collateral, based on what the lender and rules are. Before setting this up, talk to an insurance advisor, accountant, or lawyer. This way, your ownership and debt details are handled in the right way.
Commercial life insurance in Canada covers different types of insurance. The main ones are term insurance for short-term needs and permanent life insurance for long-term plans. Some kinds of insurance focus on the person. Others are about a business event.
Business life insurance in Canada is really a plan, not one type. There are a few options. You can get key person insurance in Canada, corporate-owned life insurance, shareholder protection, buy-sell funding, and loan protection.
If your company needs the skills or leadership of one main person—like the founder or a top expert—it's smart to look at key person coverage. Many business owners ask, what is key person insurance? It is a type of coverage you get for someone whose loss could badly hurt your sales, the way you work, or even your business continuity.
Most of the time, the business will own this policy, pay for it, and get the death benefit if something happens. The money from it can help cover lost sales, pay to hire and train a new person, or help the business handle its bills during this change. This is very helpful in the early years of growth and in companies with a lot of specialized skills.
In Canada, key person insurance also helps with good succession planning. It allows the business more time to act and not feel rushed. For startups, professional firms, and companies with top leaders, this key person coverage is often the smart first step.
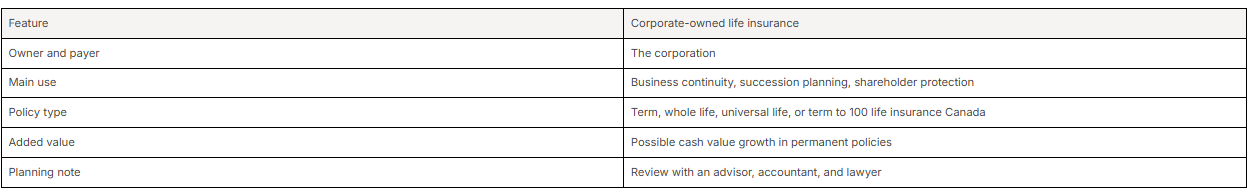
Corporate owned life insurance Canada means the corporation owns the policy, pays the insurance premiums, and receives the benefit. For many incorporated owners, this structure can support long-term planning, liquidity, and succession goals. Some permanent policies may also build cash value.
One reason owners consider it is the potential use of the capital dividend account. When structured properly, the death benefit may create capital dividends capacity for shareholders. Tax treatment varies, so do not make tax decisions without professional advice.
When more than one person owns a company, a death can raise tough questions. Who is going to buy the shares? How do you handle fair market value? What if a business partner who survives does not have enough money? This is where partnership life insurance Canada and shareholder protection insurance Canada can help.
A policy can pay out a death benefit that lets you transfer ownership the way you planned. It may keep the surviving owners and the estate from fighting. It also helps families get value from the company without ending up as owners by accident.
This works best with a strong buy-sell agreement. If your company has shareholders or partners, review the ownership terms early. It is better to plan before trouble comes than to figure things out during a crisis.
Buy sell life insurance Canada is used to give money for a buy-sell agreement when an owner dies. Many people ask, how does buy sell insurance work? It is simple. A policy is set up so there is money ready to buy shares or ownership interests if a certain event happens.
This can help with succession planning and keeping the business running. If there is no funding, a buyout could mean owners have to borrow money, sell things they own, or have fights over what the business is worth. Buy sell agreement insurance Canada is not always the same for every business, because the way a company is owned and set up in law matters.
It can help with:
Business loan protection insurance can help pay off a business loan or other debt if a key insured person dies. This is important if a company has a big business loan, a line of credit, or a loan that one owner promises to pay back personally.
The goal is easy to know. It is there to protect business income and take stress off both the company and the lender. With an insurance policy, the business does not need to rush around to find money. It will help with repaying loans or keeping business operations running. In some cases, there is also talk about getting permanent life insurance to help with policy loans or if collateral is needed.
This type of insurance can work well for startups, fast-growing firms, or stable companies. It is a good way to see how commercial life insurance and life insurance in Canada can offer risk help and not just be one policy.
Not every company needs the same plan. Still, many owners should look at their insurance options. If your income, debts, staff, or ownership might change because someone passes away, you may want to get some type of coverage.
This is important for incorporated professionals, founders, contractors, partners, and small business operators. The right business insurance depends on where you are in your journey, how much you can spend, and what you want to achieve. That’s why it is good to do a review that fits your needs.
If you have an incorporated business, life insurance can help with both your company and personal plans. This coverage may help with debts, shareholder protection, and succession planning. Owners also look at it when they want a smoother estate planning process, so things are easier to hand over later.
When one of the shareholders dies, the others need a plan. If there is no money ready, it can be hard for the other owners to buy those shares. The estate might have to wait for the money or value also. Having a strong plan in place can make things less stressful for everyone.
This is often the time when people in Canada first talk about executive life insurance and corporate life insurance. Things like ownership, tax treatment, and legal rules all play a part. Before you decide to change a policy or structure, talk to a licensed advisor, accountant, and lawyer. They will guide you on what is best for your needs.
Many small business owners, founders, and contractors often think that this planning is just for big companies. It is not. If your business needs you for work, sales, or customer ties, you can be in trouble if something goes wrong. That is why most people start to look for business insurance for entrepreneurs Canada or affordable business insurance Canada.
You do not need a setup that is hard to keep up with. Most of the time, the first thing to do is to match insurance coverage to your risk, like debt, family needs, or the kind of deal you have with your partner.
You should look at your coverage if:
There is not just one way to look at insurance coverage. The amount you need will depend on your business loan, how much money you make, how your company is set up, and who counts on your business income. Some business owners only need a simple policy, but some will need more than that.
If your company is growing, you may choose term insurance for your business loan and more permanent insurance for other needs. It is important to choose business insurance based on your real risks. Do not just guess or pick a random amount. Start by looking at the numbers, then weigh your choices.
A good way to figure out how much life insurance to get is to look at what the business would need money for if one person died. You might need to pay off debt, cover lost business income for a while, buy out someone’s share, or pay to find a replacement. The way you own the business makes a big difference. A sole owner, a partnership, and a corporation each have their own needs.
Term insurance works well for short-term debts or in the early years of a company. For longer needs, whole life insurance or universal life insurance could be the right choice. Many business owners in Canada think about if they need term insurance or whole life insurance to fit both their budget and how long they want coverage.
Think about:
Before you apply, ask why this policy is needed. Is it for debt, key person protection, shareholder funding, or long-term liquidity? Ask who will own the life insurance policy and who will get the payout. These things matter for how the coverage works.
Next, check which type of insurance is best for you and which insurance company is a good fit. Some owners want simple term life insurance. Others need permanent options, might want policy loans, or look for “term to 100” life insurance Canada for needs that last a long time.
Helpful questions include:
To sum up, commercial life insurance is a key tool for business owners in Canada. It helps you protect your company, your workers, and your money. If you know the different life insurance options, you can pick what works best for your type of business and your goals.
Having the right coverage in place keeps your business safe. It also helps with smooth succession planning and makes it easier to get business loans. Be sure to look at your needs, ask the right questions, and talk to experts if you need to.
You can make things easier by checking life insurance choices and getting a quote through PolicyNinja. This way, you get the best insurance options for your business and gain peace of mind.
Most of the time, a business cannot deduct the insurance premiums for a corporate life insurance policy as a business expense. The tax treatment depends on who owns the life insurance policy, who pays for it, and how it will be used. The rules can change, so a business owner should ask an accountant about life insurance and tax treatment before planning to take any deduction.
Corporate-owned life insurance is made for companies. These aims can be things like succession, protecting shareholders, or getting enough money for the business. Personal life insurance is mostly for helping your family if you pass away. Both types of life insurance can give you coverage and pay a death benefit. Some permanent life insurance policies may also build up cash value with time.
Start by looking at the kind of risk your business has. Then, check insurance options from more than one insurance company. A business owner needs to look at who owns the plan, how long it lasts, and what features it gives, like policy loans, if that matters. Policy Ninja can help you compare life insurance choices for your business in Canada and ask for a quote more quickly.
Cindy David, CFP, CLU, FEA, TEP, is President & Estate Planning Advisor at Cindy David Financial Group Ltd. in Vancouver. A recognized leader in wealth management and estate planning, Cindy guides clients with strategic, tax-effective solutions while championing innovation and women’s leadership in the financial industry. She is the former Chair of the Conference for Advanced Life Underwriting (CALU) — Canada’s professional association for senior life insurance and financial advisors that advances education, advocacy, and best practices in advanced planning and public policy.


