›

Life insurance for seniors Canada is still worth considering if you want to protect savings, cover final expenses, or leave support behind for loved ones. Many Canadian seniors assume coverage is out of reach, but that is not always true. Depending on your health, age, and goals, you may find affordable life insurance through term, whole life, or no medical options. The key is understanding what fits your situation instead of paying for more coverage than you need.
Life insurance remains relevant for many seniors because financial obligations do not always end at retirement. You may still want help with funeral costs, debts, or support for a surviving spouse.
For others, the goal is peace of mind. A death benefit can help family members handle final expenses without using savings or selling assets. Your coverage needs may be smaller than before, but they can still matter. The next sections explain the most common reasons older Canadians keep or buy coverage later in life.
Many seniors buy life insurance because they still want financial protection in place after retirement. The reason is not always income replacement. In many cases, it is about keeping things simple for the people you care about most.
You may want coverage for practical needs such as:
Some older adults also want a policy to protect their estate or preserve savings. The right amount of coverage depends on what you want the money to do. For one person, that may mean a small policy for funeral costs. For another, it may mean a larger policy for family support and long-term planning.
Yes, you can still get life insurance for your family as a senior in Canada. Many policies are designed to help family members manage costs that arrive quickly after a death. That can be a real relief when emotions are already running high.
A death benefit can help cover:
This matters because funeral and burial costs in Canada can be significant, while the CPP death benefit is limited. A policy can help close that gap. Instead of using retirement savings or other assets, your loved ones can use the insurance payout for immediate needs and keep your financial plans more intact.
Retirement does not always mean every bill is gone. Some seniors still carry debts such as a mortgage, personal loan, or credit card balance. In those cases, life insurance can help prevent those financial obligations from eating into the estate or creating stress for survivors.
It can also protect the savings you worked hard to build. Without coverage, family members may need to use retirement savings to cover funeral costs, estate expenses, or unpaid balances. That can reduce what is passed on to a spouse or children.
For some retirees, that makes life insurance a practical planning tool, not an extra expense. If your goal is to keep savings intact and leave a cleaner financial legacy, the right policy can help do exactly that.
Canadian seniors usually have three main life insurance options: term life, permanent coverage such as whole life, and no medical plans. Each type of life insurance works differently, so the best fit depends on your coverage needs, health, and budget.
Some people need temporary insurance coverage for debts or income support. Others want lifelong protection for estate planning or final expenses. There is no single answer for everyone. The sections below break down how each option works so you can compare them more clearly.
Term life insurance gives you coverage for a set period, often 10, 20, or 30 years. If you pass away during that term policy, your beneficiary receives the death benefit. Because it is temporary, it usually comes with lower monthly premiums than permanent plans.
This can work well if your financial needs are tied to a specific timeline. You may want coverage while paying off a mortgage, supporting a spouse, or handling other debts in retirement. Healthy seniors often find term life insurance to be one of the more affordable options.
Still, term coverage does not last forever. Available term lengths often become more limited with age, and many policies only extend to about age 85. That makes it important to check whether the policy is renewable or convertible before you apply.
Permanent life insurance is built for lifelong coverage. As long as premiums are paid, the policy stays in force and pays a death benefit when you pass away. For seniors who want certainty, that can be appealing.
Whole life is one of the most common forms of permanent coverage for older adults. It provides lifelong protection as long as premiums are paid, and many whole life policies also build cash value over time. This can make it useful for final expenses, estate planning, or leaving money behind for loved ones.
The tradeoff is cost. Permanent life insurance usually has higher premiums than term coverage because it lasts for life and may build cash value. Even so, for seniors who want stable protection and a policy that does not expire, it can be a strong option depending on budget and long-term goals.
Seniors in Canada do not always need a medical exam to get coverage. No medical life insurance is available for people who want a simpler application process or who have concerns about their medical history.
These plans usually come in two forms. Simplified issue life insurance asks some health questions but does not require a medical exam. Guaranteed issue life insurance is even more accessible, with no medical questions in many cases. Approval is often faster than fully underwritten coverage.
The tradeoff is that no medical plans tend to have higher premiums and lower coverage amounts. Simplified issue life insurance may offer much more coverage than guaranteed issue, while guaranteed issue policies are often capped at lower amounts. For seniors with health issues, though, they can still provide valuable access to protection.
Guaranteed issue life insurance is designed for people who may not qualify for other life insurance policies because of serious health conditions. The application process is simple, and many plans do not ask medical questions or require a medical exam.
That makes this option attractive for seniors who want coverage after being declined elsewhere. It can offer a way to secure a small death benefit for final expenses or basic family support when other choices are limited.
Still, there are tradeoffs you need to know. Guaranteed issue plans usually cost more, offer lower coverage limits, and often include a two-year waiting period for non-accidental death claims. It is not the best fit for every person, but it can be a practical last-resort solution when access matters most.
The biggest difference between term life and permanent life insurance is how long the coverage lasts. Term life covers you for a set number of years, while permanent coverage is built to last for life.
That difference affects cost, features, and financial security. Term is often cheaper at the start, while permanent policies can offer lifelong protection and cash value. Your type of life insurance should match your coverage needs, not someone else’s. The next sections look at both options in a more practical way.
For older adults, term life insurance works by providing financial protection during a set period. You choose a term policy, such as 10 or 20 years, and if you die during that time, the insurer pays the death benefit to your beneficiary.
This approach can make sense when your need has a timeline. Maybe you want to cover a mortgage, support a spouse for a number of years, or handle other temporary obligations. In many cases, term life insurance offers lower monthly premiums than permanent coverage for the same coverage amounts.
The challenge is what happens later. Once the term ends, coverage stops unless the policy allows renewal or conversion. Because age affects eligibility and price, seniors should pay close attention to how long the policy lasts and whether it still fits their goals over time.
Permanent life insurance stays in place for your lifetime, provided premiums are paid. That means your beneficiary receives the death benefit whenever you pass away, not only during a limited term. For many seniors, that certainty is the main appeal.
Many whole life policies also build cash value over time, although the guarantees and features vary by policy. This can support estate planning goals or simply provide a more stable long-term product than temporary insurance. Some seniors choose it because they want lifelong coverage for final expenses or to leave an inheritance.
The price is usually higher than term life, so budget matters. Still, if your main goal is permanent protection rather than short-term savings on premiums, permanent life insurance may align better with your plan.
There is no universal winner between term life insurance and whole life. The better choice depends on your financial needs, health, age, and how long you want the policy to last. That is why seniors should start with their purpose, not the product name.
Term may fit you if:
Permanent coverage may fit better if:
A simple question can help: do you need coverage for a few years, or for life? Once you answer that, the right direction becomes clearer. From there, it is easier to compare cost, flexibility, and long-term value.
Final expense insurance is a smaller life insurance policy meant to help cover funeral costs and other end-of-life expenses. For many seniors, this is one of the main reasons to buy coverage later in life.
The death benefit is usually lower than a larger family protection policy, but it can still reduce pressure on loved ones. Coverage amounts depend on your goals, budget, and health. The next sections explain what final expense insurance is, how much coverage may be enough, and who should consider it.
Final expense insurance is life insurance designed to help pay for funeral costs and other end-of-life costs. It is often chosen by retirees who do not need a large policy but still want a death benefit available for practical expenses.
This type of coverage is usually focused on smaller needs, not major income replacement. The payout can help with burial or cremation, service costs, and immediate bills that arrive after death. That can spare family members from using savings during a difficult time.
Your coverage needs will shape the amount you choose. Some people only want enough for funeral costs, while others want extra room for estate settlement or small debts. In either case, final expense insurance is about making sure those close to you are not left with urgent bills.
How much life insurance retirees actually need depends on what they want the policy to cover. Many seniors focus on final expenses first. In Canada, traditional funeral and burial costs are often estimated between $8,000 and $15,000, while some people also want funds for estate settlement or unpaid bills.
That is why smaller whole life or final expense policies are common. Some people choose enough to cover only basic costs, while others leave a wider cushion for family members.
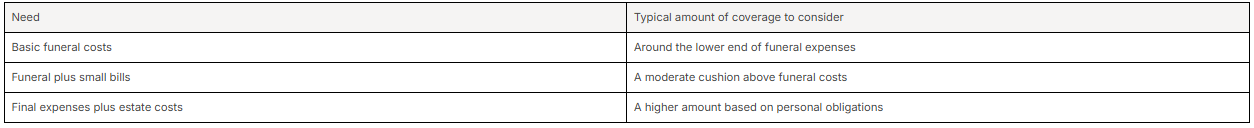
If you are unsure, add up expected final expenses first, then decide whether you also want to cover debts or leave money behind.
Final expense insurance may suit seniors who want a focused, smaller policy instead of broad lifetime coverage. It is often useful when the main goal is simple: cover funeral costs and ease the burden on family members.
You may want to consider it if:
It can work for people in good health and for those with more limited options, depending on the plan. If your needs are modest and you want a straightforward death benefit, final expense insurance can be a practical fit without paying for more coverage than you need.
Yes, many seniors over 70 in Canada can still get life insurance coverage. Eligibility depends on the insurer, your age, health, and the type of plan you want. Some insurance companies offer term life at older ages, while others focus more on whole life or no medical products.
The application process may involve health questions, a review of medical history, or no medical checks at all. Your options narrow with age, but they do not disappear. The next sections explain how qualification usually works.
Age limits vary by insurer and by product. In Canada, senior life insurance is widely available for people 60 and older, and many insurance companies still accept applications into the 70s and even beyond for certain plans.
Term life insurance usually has stricter age limits than permanent life insurance policies. Some term products are available only up to a certain age and often end around age 85. Whole life, simplified issue, and guaranteed issue policies may have higher entry age limits.
So, can seniors over 70 in Canada get life insurance coverage? Yes, often they can. The choices may be more limited, and coverage amounts may be smaller, but applying after 70 is not too late. The key is finding a policy type that still fits your age and purpose.
Health considerations play a major role in both approval and price. Insurers often look at your medical history, current health conditions, smoking status, and medications when reviewing an application. Better health can open the door to lower premiums and more policy choices.
Do seniors in Canada need to take medical exams to get life insurance? Not always. Fully underwritten policies may require a medical exam and more detailed medical questions, but no medical options are also available. Those can be useful if you want a faster or simpler path.
Healthy seniors may benefit from going through underwriting because they can sometimes get better rates than they would with no medical coverage. If you have health concerns, simplified issue or guaranteed issue can still provide an option.
Having health issues does not automatically stop you from getting coverage. Many seniors with health conditions such as high blood pressure, diabetes, heart disease, or a history of cancer may still qualify for life insurance, though the type of plan and price can change.
Common options include:
Affordable options for seniors over 70 do exist, but you may face higher premiums than a younger or healthier applicant. That is why it helps to compare several choices instead of assuming there is only one route. In many cases, the best value depends on balancing accessibility, coverage, and cost.
Life insurance rates for seniors in Canada vary widely. Monthly premiums depend on age, health, smoking status, the type of policy, and the coverage amounts you choose. That is why two people of the same age can receive very different pricing.
Based on the compiled information, a $250,000 policy can range from under $100 per month at age 60 for some term coverage to over $2,000 per month at age 80 for certain whole life plans. Your amount of coverage should reflect your financial needs, not guesswork.
Premiums are based on risk, and insurers look at several details before setting a price. For seniors, age and health usually have the biggest impact. As age increases, choices may narrow and rates often rise.
The main factors include:
Smoking status also matters, and women often receive lower pricing than men. In general, fully underwritten plans can offer better rates for healthy applicants, while no medical policies usually cost more. If you want to control premiums, choosing only the coverage you truly need is one of the smartest first steps.
The sample life insurance rates below show how premiums can change with age. The examples use $250,000 of coverage and compare 10-year term life insurance, 20-pay whole life, and simplified issue coverage. These figures are illustrative only and are not guaranteed quotes. Actual premiums vary based on factors such as age, health, smoking status, sex, insurer, and policy type.
You can see that higher premiums become more common in later years, especially for permanent life insurance and no medical options. That is one reason many seniors apply earlier if they can.
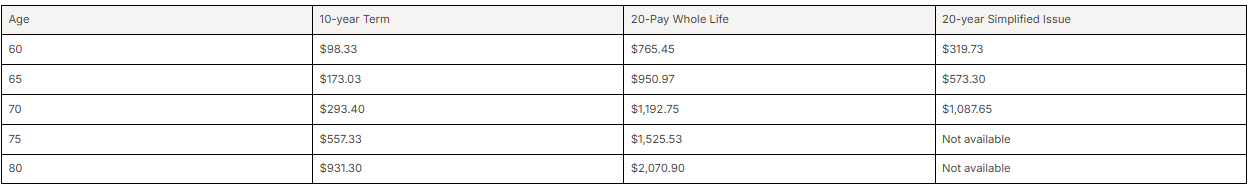
These sample monthly premiums illustrate why comparing policy types matters so much.
The most affordable life insurance options for seniors in Canada are often term policies for healthy applicants and smaller coverage amounts for those with limited needs. Buying earlier can also make a noticeable difference in price and product availability.
To reduce costs, focus on practical steps:
Healthy seniors may save by choosing fully underwritten coverage instead of no medical plans. If your goal is final expenses only, a smaller permanent policy may be enough. The best way to find affordable life insurance for seniors is to compare options side by side rather than picking the first quote you see.
Comparing life insurance quotes is about more than finding the lowest monthly cost. You also need to check what the policy includes, how long the coverage lasts, and whether it fits your actual goals. That is how you find the right life insurance, not just the cheapest option.
Because insurance companies use different pricing and underwriting rules, quotes can vary more than many seniors expect. A careful policy comparison can help you avoid overpaying or choosing insurance coverage that does not match your needs.
When reviewing insurance policies, start with your purpose. Are you trying to cover final expenses, protect a spouse, or leave money behind? The best life insurance is the one that matches that goal without stretching your budget.
As you compare quotes, look closely at:
It also helps to review how much coverage you really need. A lower premium can look attractive, but it may come with less protection or a shorter policy term. Good comparison means balancing cost, policy features, and your real coverage needs rather than focusing on price alone.
If you are wondering how to compare life insurance in Canada as a senior, the easiest approach is to review quotes from more than one insurer in one place. That helps you see how prices, underwriting rules, and coverage options differ based on your age and health.
PolicyNinja can be a helpful place to start that process. Through https://www.policyninja.co/, seniors and adult children helping parents can compare life insurance quotes, review policy comparison details, and explore coverage options without added stress.
This matters because one insurer may be more flexible for certain health conditions, while another may offer a better rate for smaller coverage. Instead of contacting several insurance companies one by one, using a comparison platform can make the process clearer, faster, and easier to manage.
Many seniors make avoidable mistakes when shopping for life insurance policies. One common issue is waiting too long. As age rises, rates usually increase and product choices can become more limited. Another is choosing coverage amounts without first reviewing financial needs.
Try to avoid these missteps:
It is also easy to overlook estate planning goals when thinking only about funeral costs. Some seniors need a policy for debts, a spouse, or estate settlement, not just final expenses. A careful comparison can help you avoid paying for the wrong policy and improve the odds of getting coverage that truly fits.
Understanding the nuances of life insurance can lead to better financial decisions. Common concerns among seniors include eligibility and the types of coverage available. Many wonder if health issues will disqualify them or raise premiums. Exploring different policies can reveal valuable options, such as term life insurance and whole life policies tailored for seniors. The application process often raises questions about medical exams, with many opting for no medical life insurance for added convenience. Engaging with knowledgeable insurance advisors can streamline the journey toward coverage that meets your needs while providing peace of mind for family members.
Yes. Many seniors can get life insurance without a medical exam through no medical life insurance options. Some plans ask a few medical questions, while guaranteed issue coverage may ask none. Your health considerations still affect cost, coverage amount, and which product is available.
It depends on your coverage needs and financial needs. Many retirees buy life insurance mainly for final expenses, small debts, or support for a spouse. Start by adding expected funeral costs, unpaid obligations, and any amount of coverage you want to leave to loved ones.
Yes, although life insurance rates are usually higher premiums after 70. Affordable life insurance may still be available through smaller term policies, whole life with lower coverage, or simplified issue plans, depending on your health conditions. Comparing quotes is one of the best ways to find value.
Finding affordable life insurance for seniors in Canada is an important step to ensure financial security and peace of mind. As we’ve explored throughout this guide, there are various options tailored to meet the specific needs of older adults, whether it’s term life, permanent life, or final expense insurance. Understanding your coverage needs and comparing quotes can help you make a well-informed choice. Don’t hesitate to reach out for guidance as you navigate your options. For a straightforward way to compare senior life insurance policies, visit PolicyNinja today and get a quote that fits your needs.
Cindy David, CFP, CLU, FEA, TEP, is President & Estate Planning Advisor at Cindy David Financial Group Ltd. in Vancouver. A recognized leader in wealth management and estate planning, Cindy guides clients with strategic, tax-effective solutions while championing innovation and women’s leadership in the financial industry. She is the former Chair of the Conference for Advanced Life Underwriting (CALU) — Canada’s professional association for senior life insurance and financial advisors that advances education, advocacy, and best practices in advanced planning and public policy.


