›

Knowing how much life insurance you need in Canada can seem hard at first. Maybe you want to make sure your income will be safe, pay off a mortgage, or help your family if you are not there. The good thing is, you can find the right amount of life insurance by looking at what you spend and what you want for the future. This guide shows the steps for finding life insurance coverage in a clear way. You will be able to pick the insurance coverage that matches your needs and your life in Canada.
Choosing the right coverage amount is important. Your family may rely on the death benefit to pay everyday bills, debts, and other costs. If your insurance coverage is not enough, it may not give your loved ones the financial support they need.
Life insurance needs are personal. Your financial situation, income, and what you are responsible for will help to decide what enough life insurance means for you. To figure out how much life insurance you need in Canada, start by looking at what your family would need for support or to pay off debts.
If people count on you, life insurance coverage helps protect the life they know. This insurance can pay for lost income, help with housing costs, and give your family time to get used to this change. That support makes tough times a bit easier.
Your life insurance policy should match your real financial situation. Think about what your partner, kids, or others who depend on you would need if your income was gone. Things like food, utilities, rent, and child care keep going. This is a big reason many of us get personal life insurance plans.
You may need more insurance coverage if you have dependents or a mortgage. Bigger needs often mean more coverage. Family life insurance Canada is most important when people rely on your paycheck or your work at home, even if you do not get paid for it.
Debt does not go away when someone dies. That is why you should include all your outstanding debts in your insurance coverage estimate. This means you need to think about credit cards, car loans, student loans, and other credit lines you may have.
Your mortgage is important too. Some people get mortgage insurance Canada, but you should know that this type of mortgage insurance usually pays the lender. A regular life insurance policy from Canada pays the amount of money to your chosen beneficiary. This option gives your family more control over how the money is used.
If you have a big mortgage or many debts, you may need to get more coverage in your insurance policy. Many people use term life insurance Canada for these needs because it often matches the number of years left on your mortgage or loan. This way, your family will get what they need when you are gone.
When you have dependent children, your coverage needs usually go up. Kids need food, housing, clothes, activities, and child care for some years. If one parent passes away, the other may need more financial support to help keep the family life steady.
It is smart to think about future education costs, too. When you ask how much life insurance you need, you should add in these costs. School after high school can be a big part of what you have to pay.
A registered education savings plan can help take care of some costs. But it might not be enough on its own. The advice often uses the RESP lifetime limit of $50,000 per child to show how much you might need. If you want to make sure your child’s school costs are covered, use that amount in your coverage needs estimate.
There is not one simple answer when it comes to the right amount of life insurance for Canadians. The coverage amount will be different for each person. It depends on your annual income, your debt, your mortgage, your children, and the type of financial support you want to leave for your family.
When you think about the amount of life insurance you need in Canada, focus on the costs your family would have if you were not there. These costs can include income replacement, paying off loans, education costs, and final expenses. It can help to look at each part on its own. This way, figuring out your insurance needs will feel much easier.
Income replacement is one of the main things to think about when you look at life insurance needs. You should ask yourself, how much of your yearly pay does your family need if you are not here? Most times, this is the heart of the figure you need.
Next, pick the number of years the income needs to last. Some people choose the years until their children finish school. Others use the years until retirement. The info shows that if you make $50,000 a year and want to replace that lost income for 20 years, you will need $1,000,000.
This is a simple way to find out how much life insurance you need in Canada. Take your income, then multiply it by the number of years you need to cover. Add any other big costs. This method gives you a good starting point to figure out your life insurance needs.
Debt can change your life insurance coverage needs fast. If your family would need to pay off your loans after you die, you should add those numbers when you figure out how much coverage you need. This covers things like credit cards, student loans, car loans, and any other outstanding debts.
Your mortgage balance is usually the biggest thing you owe. Some people in Canada look at the difference between a personal life insurance policy and mortgage insurance. The main thing that makes them different is where the money goes. Mortgage insurance will often pay the lender. A personal policy pays your chosen person, or your beneficiary. They get to decide what to do with the money.
So, do you need more life insurance coverage if you have people who count on you, or if you have a mortgage? Most of the time, yes. When you have a home loan and kids, your family is likely to need more money. This way they can keep the home and cover other needs if something happens to you.
Childcare costs are easy to forget, but they are important. If one parent dies, the one that is left may have to pay for daycare or get help at home. This can really change the amount of coverage you need in your life insurance.
Education costs should be counted in your insurance needs as well. There are costs for college or university, books, a place to live, and more years in school. All of these can really add up. Some people use RESP planning to find out how much they may need.
So, it is a good idea to count future expenses like a child’s education when you think about your life insurance. If you want your family to have financial support for a long time, include both childcare costs now and education costs later when you pick the amount of coverage you want.
Final expenses are less than what you pay for a house loan, but they are still important. A life insurance policy can help your family pay for funeral costs and other bills right away. This lets them avoid using money they save for needs they have every day.
The numbers here show that funeral costs can be near $15,000. This might not be what every family has to pay for their final expenses. Still, it lets you see why you should not forget about these costs when you choose the amount of money for coverage.
If you wonder how much life insurance you need in Canada, you should add your final expenses to the rest of your costs. These are a real part of the death benefit that your family could need in the first days and weeks after you are gone.
Life insurance does more than just pay off bills. It can help your family keep their way of life and reach their long-term financial goals. You may want your spouse to stay in the same house, pay the usual costs, or keep saving for retirement.
That is why enough life insurance is about more than just paying off debt. It can also match goals like giving support until retirement or covering future housing needs. In the sample, one way is to look at your salary up to retirement. This can be a better guess for how much you need than using a quick rule.
You should look at your investment accounts and your savings before picking the amount of coverage you want. The money you already have can lower how much new life insurance you need. This fits well with your life stage and your family’s needs.
Your life stage can change the size and reason for your insurance coverage amount. For example, a single adult without a mortgage will need much less insurance coverage than someone with young children, a home loan, and many monthly bills.
That is why you should review your insurance needs along with your life situation. The coverage amount that works for one family may not work for another. To know how your life stage changes the amount of life insurance you need, look at who depends on you and what kind of financial support they will need.
A single person with no dependents may not need much coverage. If there is no one who depends on your income and you do not pay a mortgage, you might need less coverage or even none for now. It depends on your financial situation.
Once you have a partner, kids, or you share debt with someone, things change. A life insurance policy is then more important because other people will be hurt financially if something happens to you. The amount of coverage usually goes up if you have these extra duties.
Families often need more of a safety net because there are more things going on. Bills like rent or mortgage, child care, food, and school costs can add up over many years. That is why family life insurance Canada is often focused on dependents and bills you share.
Young parents usually need a higher coverage amount with life insurance. They have growing responsibilities. Young children need care for many years. If one parent is gone, the other may need help replacing income or paying for child care.
Family life often costs more with time. Education costs, bigger homes, and daily bills all change how much coverage you may want. Many parents start to ask when to buy life insurance. For most, it should be as soon as others count on them.
If you are starting a family, life insurance for parents Canada can give financial support during important years. The goal is not to be perfect. It is to make sure your family can go on without big changes if something happens.
When you own a home, you have to check the mortgage balance before picking the amount of life insurance. That debt may be the biggest thing your family would have to pay if you die. Paying off the mortgage can help keep your family’s home safe.
Mortgage insurance is something people think about, but it is not like a regular policy. Mortgage insurance pays the lender. A personal policy pays your beneficiary. Then, they can use the money to pay the mortgage, handle other bills, or spend it where it is needed most.
You do not need to insure your home’s value. What matters is the mortgage balance and any outstanding debts. When you look at mortgage life insurance Canada versus personal life insurance, there is more flexibility with a personal policy.
Business owners may want life insurance for family and work needs. Your loved ones may need your income, and your company may have bills and costs that won’t stop if you are gone. That means you may need to get a higher amount of coverage.
Some business owners hear about key person insurance. If you have ever wondered what key person insurance is, it helps protect a company if someone important passes away. People may talk about executive life insurance Canada, corporate owned life insurance Canada, and business continuation insurance Canada in these talks.
Entrepreneurs may also see buy sell life insurance Canada, buy sell agreement insurance Canada, how does buy sell insurance work, shareholder protection insurance Canada, partnership life insurance Canada, and business succession insurance Canada. If you run a company, a business insurance advisor Canada can help you find affordable business insurance Canada, business insurance for entrepreneurs Canada, business overhead insurance Canada, and business overhead expense insurance.
Before you use a life insurance calculator, get the the numbers that matter for your insurance needs. This helps you make a better estimate and stops you from missing big financial obligations. It also makes it easy to compare insurance coverage later.
Start with your annual income, regular expenses, debts, and any savings or current coverage. These numbers help you work out the amount of coverage you may need. When you have them ready to go, the life insurance calculation is much easier.
First, get the numbers for the money you and your family bring in and spend. These show how much money would be needed if you could not earn anymore. This helps you understand your real insurance needs, not just guess.
Look at your earnings and the monthly bills. Be honest about what your family needs to get by. That is the best way to know how much money you should plan for.
Useful details to gather include:
Next, write down every debt that your family may have to pay. Many people miss some of the amounts, especially if there are different balances on many accounts. Still, these debts can change how much coverage you need.
Don’t just focus on the mortgage. Smaller debts can come together and become a burden for your family. Add any loans that you plan to take soon if they are in your plans for the near future.
Your list could have:
Start by listing everyone who counts on you. This list may have your spouse, your kids, or anyone else who relies on your pay or help at home. People who depend on you usually be the main reason for coverage needs.
Think about what the people on your list will need and how long they will need help. This lets you guess the amount of money needed for both today and one day in the future. It also helps you keep the math real and simple.
Think about needs like:
Last, check the assets and coverage you already have that might help your family. Savings and investments can lower how much new life insurance you’ll need to buy. Doing this can stop you from getting more insurance than needed.
You should also look at employer life insurance Canada, but you need to be careful. Group coverage through work is often only two or three times your pay, based on gathered information. It can give your family some financial support, but this support is usually small and depends on your job.
Review these things:
If you want an easy way to figure out your coverage needs, break it down into steps. You can do the math on your own, follow a rule of thumb, or use a life insurance calculator to check your numbers. Any of these can help you.
The best way is to look at your real needs first. Add up your debts and what you want to provide, then see how much you have in savings or in current life insurance. This way, you will get a better idea of the amount of life insurance you need instead of just picking a number by using one shortcut.
Start by putting together all the numbers linked to your household. This means adding up your annual income and any other income, debts, and monthly costs. If you miss this step, you could end up with an estimate that is too high or too low.
A clear and easy list helps you better see your life insurance needs. It is also useful when you want to compare policies or get life insurance quotes Canada. Keep these numbers basic and real so you know what you need.
You should collect these:
First, think about how long your family would need income replacement. This will depend on the age of your kids. It also depends on how much your partner can earn and what your bigger plans are. There is not just one answer that fits all.
Next, take your annual income and multiply it by the number of years your family will need help. For example, the compiled example uses $50,000 as annual income for 20 years. That adds up to $1,000,000 in lost income support. This is a simple way to figure out a large part of the need.
Questions that can help you decide:
After you look at income replacement, add your larger one-time costs. These include debts, your mortgage, education costs, and final expenses. All these can make the amount of life insurance you need much higher than what you first thought.
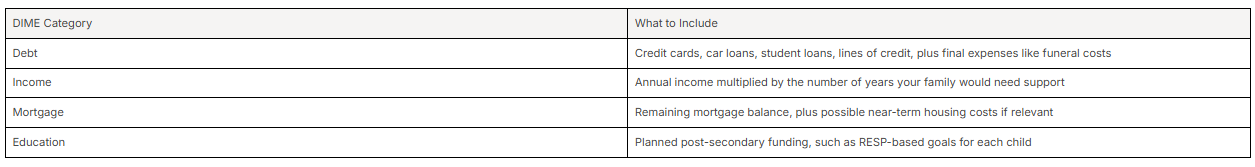
The DIME approach is useful because it puts the main parts into one big number. The example in this method adds up debt, funeral costs, mortgage, and education savings goals to get a more complete estimate.
Add things like:
After you know your total obligations, take away what your family can use right now. This includes money in savings, investments, and any insurance coverage you have. You do not have to cover every dollar from the beginning.
The advice shows you should take away liquid assets like savings, investments, RESPs, and all current life insurance. Group coverage you get at work counts too. Just remember, group coverage from your job may not always be there.
Possible offsets include:
A life insurance calculator Canada can help you get a quick idea after you put in your numbers. It is good when you need a starting point or want to look at different coverage needs. Many people use one before they ask for life insurance quotes.
Are life insurance calculators good for Canadians? They can help, but they only use the numbers that you enter. They are best as a guide. They do not give you the final answer. You may still change it for your family, what you owe, and what you already have.
Use an insurance calculator to try out:
There are some simple ways to figure out life insurance needs in Canada. None of them fit everyone, but each one can be a good starting point. The best way for you will depend on how much detail you want.
If you want to know if there is a recommended formula for life insurance needs in Canada, the answer is yes. There are a few common ones. These include the DIME formula, or a rule of thumb like using salary multiples, and a life insurance calculator.
The DIME formula is one of the clearest ways to estimate coverage needs. It stands for Debt, Income, Mortgage, and Education. You add these categories together to get a broad starting total. For many families, it captures the biggest financial obligations in one method.
This approach works well because it asks practical questions. How much debt do you have? How many years of income should be replaced? What is left on the mortgage? How much do you want set aside for education costs?
Here is the example structure from the compiled information:
One common rule of thumb is to buy an amount of coverage that is about 10 times your yearly salary. This way is quick, simple, and something that a lot of people remember. That is why many people use it as the starting point.
But, this method has its limits. The information shows that this rule can be random at times. A better way might be to figure out your full salary until you retire. It also helps to think about the fact that some personal costs would not be there after you die.
So, see this rule more as a starting point and not your only answer. The amount of coverage you need should still depend on your debts, kids, and insurance needs. Using a simple salary rule can be good, but you should still take time to review your full needs.
Future expenses are important when you look at life insurance. This is because life insurance is to help your family for more than just a few months. If you have young children, you may need to make sure your coverage can help with costs for years down the road.
Education costs are a good example of what you might have to plan for. The information shows that a lifetime RESP fund goal of $50,000 for each child is one amount to consider. This can help a family make a simple guess about part of the amount of life insurance they will need for the future.
Future expenses may include:
If you think about your life insurance and these coverage needs, you can make a good plan for your loved ones.
Many people in Canada may not think enough about their life insurance needs. Some people pick the amount of coverage by only looking at salary. Others do not include big costs, like debts, child care, or funeral costs. Both of these mistakes can cause bad planning.
You want to make sure you have enough coverage, but that you are not paying insurance premiums for unnecessary coverage. It is best to look at your full situation. This includes family costs, employer benefits, and your goals for later in life. There are a few common errors that people make most often with their life insurance.
One common mistake is skipping hidden costs. People count the mortgage and main debts, but they do not include child care, school fees, or one-time bills after death. These small bills can add up fast and raise the coverage amount more than you think.
Final expenses get missed as well. Funeral costs, household needs right after, and short-term help for your family can come up quick. If you do not include them, your family may use their savings right away.
You should think about inflation, too, when looking at future costs. The material does not give a formula for it. It does say that school costs and long-term support go up over time. This is why picking only the minimum coverage amount could leave your family short later.
Workplace coverage can be helpful, but it is not smart to rely only on employer life insurance. The information shows that group life insurance usually covers two to three times your salary. For many families, that is not enough.
There is another problem too. Group life insurance is linked to your job. If you switch jobs or lose your job, your coverage may end. That can make a gap at the time your insurance needs are growing.
A personal policy can fill that gap and give more stable financial support. If you already have workplace coverage, you should include it in your plan. But do not think that it covers everything. Many Canadians need more life insurance than their job offers.
The insurance policy you pick changes how much coverage you get and what it costs. There are many people in Canada who use term life insurance for needs that last for a certain number of years. Permanent life insurance is often for goals that last longer.
If you have someone who relies on you or you have a mortgage, term coverage is a good choice. This is because these needs last for a set time. Permanent coverage does something different. So, it's smart to look at both types of life insurance and compare them.
Term life insurance is often used to help with income replacement. It can also help pay off a mortgage or cover child costs during your busiest years. Because of this, the coverage amount for term life insurance can be bigger than what some people think. This type of life insurance is set up to give what you really need for a set number of years.
The information pulled together here gives an example. A 20-year term policy can give a total coverage amount of $1,590,000 by using the DIME formula. It also shows that a 20-year term policy might be about $30 to $60 a month for some people. The cost can change for different buyers.
People often get a term policy for these uses:
Permanent life insurance lasts your whole life, not just for a set amount of time. This article talks more about term insurance, but permanent life insurance is still something many people in Canada compare when looking at their options.
When you check out your choices, you may find types like whole life insurance, universal life insurance, and term to 100 life insurance Canada. If you are searching for term vs whole life insurance Canada or want universal life insurance explained, remember one thing. Permanent life insurance is often used for different reasons than term insurance, which is more about temporary help for family.
Some people get permanent coverage to help with financial support that lasts a long time. Some use it along with term coverage. The right amount of coverage depends on your family, your debts, and your budget. There is no set answer.
Yes, your coverage amount can change with time because your financial obligations are not always the same. You may have a new child, get a bigger mortgage, take on more debt, or want to grow your business. These can all make you need more coverage.
On the other hand, if you pay off loans, your children get older, or you have more savings, you might feel you do not need as much coverage. That is why many Canadians go over their life insurance policy as life changes.
The key is to make sure you have enough life insurance for your needs today, not base it on what you needed years ago. This matters if you first bought a small insurance policy when you were younger. As your budget, family, and goals change, your life insurance policy may need an update too.
A life insurance review helps when your life changes. Getting married, having kids, buying a house, or starting a new job can affect your coverage needs. If you pay off a lot of debt or save more money, this can change things too.
Think about your life insurance coverage based on your current financial situation. Ask if your family would still have what they need if you died today. If you are not sure, it might be a good time to check your insurance coverage.
This matters for people looking for life insurance for young adults Canada or life insurance for parents Canada. Your insurance needs at age 25 can be very different at age 35 or 45. Reviewing your coverage every few years helps make sure your life insurance coverage still matches your needs.
You may not keep the same insurance policy all your life. Some people get another term policy when they buy a house or after they have kids. Others lower their coverage amount once their debts go down and savings go up. There is information saying that using more than one term life policy can help with different needs.
This can be a smart move. For instance, one term policy can be for your spouse until he or she retires. A smaller policy can be for your children until they finish school. This gives your family the money they may need while not keeping the same high amount for too long.
Permanent policies may work in a different way, but the main point is the same. Your insurance coverage should match what you really have to take care of. If things change for you, the insurance policy mix you have might need to change too.
Life insurance costs in Canada change based on a few things about you, the amount of coverage you pick, and the kind of policy you choose. The info shared can help give a simple idea for term life insurance. A 20-year term policy might cost you between $30 and $60 every month. If you are younger, healthier, or female, you may pay less. Some people may pay more, depending on their situation.
There is no set minimum for recommended life insurance coverage for a Canadian family because the need changes for everyone. For example, a family with a big mortgage, young children, and only one main earner will likely need more insurance coverage than a family with little debt and good savings. This is why it is important to look at life insurance costs along with what your family really needs, not just by the numbers alone.
Life insurance rates in Canada depend on risk and what is in your policy. Insurance companies look at your age, your health, and how much coverage you want. If you buy when you are younger, you would usually get a lower rate.
The gathered facts show that the way you live, like if you smoke, can make your price go up. What you need for coverage plays a big part also. A policy with a bigger amount of coverage will cost more than a smaller one, even when both are term life insurance plans.
Common things that set the price include:
Comparing life insurance quotes in Canada helps you see what the coverage will cost. When you know the amount of coverage you want, you can check insurance policies from different companies. This way, you do not have to guess.
An insurance calculator or life insurance calculator is useful before you ask for quotes. It gives you a fast estimate. You will not be shopping without knowing what you need. After that, you can look at each insurance policy for price and how well it matches your needs.
When you check quotes, pay attention to:
Comparing insurance coverage options should begin with your own numbers. You can use an insurance calculator to get a quick estimate of what your family will need. After you have an idea, look for life insurance policies that fit that number. Then, you can compare different term policy options, see each price, and check how well each choice matches your timeline. This way, you can make choosing life insurance coverage less stressful and more clear.
If you already have savings or investments, you might still need life insurance. The information says to take those assets out of your total need, but do not leave them out completely. Savings may help lower the gap, but they do not always take care of all of your life insurance coverage needed. A careful comparison lets you see what is still missing.
Online tools can help make the first step a lot easier. A life insurance calculator Canada lets you try out different numbers, like how long you want to replace your income, the debts you owe, and what savings you have. This gives you a real range for your coverage needs.
These tools help a lot if you are still thinking about how much life insurance you want. They take a hard question and make it much simpler to answer. You can use the results when you check life insurance quotes.
A calculator can help you compare:
PolicyNinja is a good place to see life insurance Canada plans side by side. It makes the process easier and not too much to handle. If you want a simple way to look at life insurance Canada and check your coverage needs, start with a platform made for this job. You can visit PolicyNinja at https://www.policyninja.co/ and see the choices or get a quick quote.
This site works if you need term life insurance, permanent life insurance, or want to find the right amount of coverage for your family. It is also useful when you search for 'life insurance broker near me' or want to know more about life insurance explained Canada. It helps find a clearer path for you.
PolicyNinja may help people in many ways:
To sum up, picking the right life insurance coverage amount in Canada helps keep your family safe with money if something happens to you. You need to look at things like how much income replacement your family will need, what outstanding debts you have, and what future expenses could come up. This helps you put together a plan that fits your life.
Try not to make common mistakes and use tools like a life insurance calculator to get a good idea of how much coverage you should have.
Your life can change, so it’s important to look over your insurance coverage now and then to make sure it still works for you. If you are ready to find the right coverage amount, you can compare life insurance options and get a quote from PolicyNinja. That way, you and your family can have peace of mind.
Yes, they can. Your savings and investments can help lower the amount of life insurance you may need. But they might not be enough to fully take the place of life insurance coverage. If your family will still need some financial support for things like income, debts, or the house loan, life insurance can help cover that gap.
Yes, you need to count future costs like your child's schooling when you choose your life insurance coverage. This makes sure your loved ones get the right financial support for their needs and schooling if you are not here.
The lowest amount of life insurance coverage that is often suggested for a Canadian family is about 10 to 15 times the main earner's annual income. This number helps to make sure that their loved ones will have money , if something happens to them. It can cover things like the mortgage, schooling, or basic costs that come up after someone is gone.
Online life insurance calculators are a good starting point for Canadians who want an idea of how much they may need. But the accuracy of these calculators depends on what you put in and what they assume. You should use them to get a sense of things, but also think about your own situation. It can be best to talk to a professional for advice that fits you.
To begin, comparing life insurance in Canada is important. Check different policies for what they cover, how much you pay, and the terms they offer. Ask for quotes from different providers. This will help you choose the one that fits your needs and goals.
When you pick your life insurance coverage amount, think about your income, any debts you have, and what your family needs. A common way is to take your annual income and multiply it by 10 to 15. Make sure you also think about things like paying for a home or college in the future. This helps make sure your life insurance coverage gives good protection for your loved ones.
PolicyNinja makes it easy for people in Canada to compare life insurance. The platform is simple to use and gives quotes that fit what you need. You can look at different policies next to each other. This helps you see all the details clearly. It saves you time, and you might spend less money. With PolicyNinja, you can find good coverage that works for you.
Cindy David, CFP, CLU, FEA, TEP, is President & Estate Planning Advisor at Cindy David Financial Group Ltd. in Vancouver. A recognized leader in wealth management and estate planning, Cindy guides clients with strategic, tax-effective solutions while championing innovation and women’s leadership in the financial industry. She is the former Chair of the Conference for Advanced Life Underwriting (CALU) — Canada’s professional association for senior life insurance and financial advisors that advances education, advocacy, and best practices in advanced planning and public policy.


