›

It can be tough to pick from all the Canadian life insurance companies. The names and what they offer can look the same. You want real facts, good insurance quotes, and an insurance policy that is right for you and your family. You might need to think about debt and long plans too. This guide will help you know about the big providers. It shows what they have and how you can compare them.
You get tips so you can look at each insurance company in a way that fits your life and your needs. Not every answer works the same for all people in Canadian life insurance. This is about finding the one that will be best for you.
When people want to know the top Canadian life insurance companies and how they stack up against each other, the answer often starts with size. It also comes down to what product range a company offers, how good their service is, and if they are easy to work with. You and I will often hear names like Canada Life, Sun Life, Manulife, iA Financial Group, Desjardins, RBC Insurance, BMO Insurance, Equitable Life, Empire Life, and Foresters Financial.
But the best life insurance for you can be different for someone else. One insurance company can be great for term coverage. Another can be right if you want help with estate planning, no-medical options, or strong advisor support. The next sections will show you what the top life insurance companies in Canada offer in a way that's simple to follow.
Canada Life is one of the oldest and best-known life insurance companies in Canada. The company offers a lot of life insurance coverage. You can also get health, disability, and workplace benefits. Many families find that it is easier to handle their life insurance with Canada Life because the company does so much at one place.
The term options at Canada Life are very flexible. You can get a plan that lasts just 5 years, or one that goes up to 50 years. Canada Life also has participating life insurance and universal life. You can get a permanent plan that may build cash value. With some plans, you can take out a policy loan or withdraw money. Also, if you die, the death benefit is there to help your loved ones.
When you compare Canada Life to Sun Life and other insurance companies like Manulife, you will see that Canada Life has more long-term choices and a longer history in Canadian life insurance. If you want flexible insurance plans just for yourself, or a family life insurance Canada plan, Canada Life is a good choice to look at.
Sun Life Financial is one of the biggest life insurance companies in Canada. The company has a strong place in the market, a big advisor network, and many choices for term life insurance and permanent policies. Many people know the name because it has been there for a long time and is trusted.
You can pick a term that lasts anywhere from 5 to 40 years, depending on which product you choose. Sun Life gives you a wide range of products, with coverage that starts with simple online options, or you can get much more coverage by working with an advisor. On the permanent side, they offer whole life, participating life, and universal life insurance. This is good for people who want to know about universal life explained in a simple way.
When it comes to customer service, Sun Life is thought to be a good choice. The support is dependable, and it covers all of Canada. If you are looking in Canada for flexible life insurance and want help from an advisor, Sun Life is worth a closer look.
Manulife is the biggest Canadian life insurance company in the world. It has many types of life insurance policies. That means you can pick from cheaper term life, guaranteed issue, easy issue plans, and a few permanent choices. Canada Life and Sun Life are often compared with Manulife because of this.
With the CoverMe term products, you choose either a 10-year or a 20-year term, and your price stays the same for that full term. CoverMe Term 10 renews every 10 years up to age 85, and CoverMe Term 20 renews every 20 years up to age 89. Neither one asks for a new medical exam or questionnaire at renewal, though your rate goes up based on your age at that point. You can also convert your CoverMe term coverage to permanent life insurance before age 70 without proving you are in good health.
Manulife also has life insurance options where you just have to answer a few questions or no questions at all. These work for people who may not get standard life insurance from another insurance company. For permanent life insurance, you can get universal life or a policy that may build cash value over time.
If you want to compare Canada Life, Sun Life, and Manulife, you may notice Manulife stands out because it offers many products and covers different health needs. Manulife on its own can be a good pick for life insurance for parents Canada families want or life insurance for young adults Canada families need.
Industrial Alliance, also called iA Financial Group, is one of the top providers in Canada. It offers both temporary and permanent life insurance. The mix of products gives options to families, professionals, and business owners who may want more than just basic term insurance. This helps if your needs change over the years.
For term insurance, iA Financial has plans like Access Life and Pick-A-Term. Access Life is the no medical option. There is no medical exam, and you only answer a few questions about your health. Your answers place you in a health step, and that step sets how much coverage you can get, from $10,000 up to $500,000, and whether you are offered permanent V100 coverage or a 15, 20, or 25-year term. Pick-A-Term is the fully underwritten plan, and it lets you choose any term from 10 to 40 years instead of a preset 10, 20, or 30. Their term coverage gets good feedback for the conversion options, because iA term policies are renewable and convertible into permanent life insurance until age 71.
iA Financial also has whole life and other plans that can help with estate planning or your business. So, if you want executive life insurance Canada, buy sell life insurance Canada, or business succession insurance Canada, then this is one company to look at.
Desjardins Insurance is a big name in Canada when it comes to life insurance. The company is known for being flexible with its coverage. It has many products you can pick, like term life insurance, permanent plans, and universal life insurance. You can also get things like critical illness and disability insurance. There are other wealth products too. This is good if you want to keep all your insurance and money planning with one insurance company.
One thing that stands out with Desjardins is that you can bundle different products. If you have other products with them, your life insurance or universal life insurance may be easier to handle. It also makes sense if you want to tie your insurance with planning for retirement or for long-term money goals. Your insurance premiums still depend on things like your age, health, and which policy you choose. But you have many good choices.
People say Desjardins is a good pick if you want an insurance company from Canada that has a lot of products. It can work well for families, professionals, or anyone who wants to look at whole life and critical illness insurance side by side.
RBC Insurance is on many comparison lists because it is easy to use and people know the banking brand. If you are someone who banks with RBC, you might find it simpler to get your life insurance through the same insurance company. That is why a lot of buyers put RBC Life Insurance on their shortlist when they look for life insurance companies.
RBC gives people life insurance and also other choices, like health and travel insurance. It is a good pick for people who want flexible coverage options with a known financial group. Many buyers say good customer service starts when you can get to your provider fast, use tools you already know, and deal with a company you trust.
When people in Canada want to know which Canadian life insurance companies have great customer service, rbc insurance often comes up. You should compare it if you want easy service, strong help, and a company with offices across the country.
BMO Insurance is a good choice if you want to work with a big and well-known insurance company in Canada. It offers flexible choices that can fit many needs. Many people look at BMO Insurance when picking term life, critical illness, or plans to protect their family. It should be on your list when you compare life insurance companies in Canada.
The first thing people look at is finding a provider that fits what they want. Ask yourself if you only need affordable coverage for now or if you want features that last longer. BMO Insurance might seem right if you want easy-to-understand coverage options that come from a trusted name. For people who want stability and simple access to the products, this can matter a lot.
Make sure to compare BMO Insurance with other life insurance companies. Think about your age, health, and how much you can pay. If you are looking for lower cost term coverage, look at BMO along with Canada Life, Sun Life, and RBC Insurance. Do not just pick any one company right away. Always see which one is best for you.
Equitable Life of Canada stands out because it gives buyers personal service. It also works as a mutual insurer. For those who want a process that includes more talk and attention, this can be a good pick. The company has insurance policy choices for life insurance, savings products, and group benefits.
Equitable Life has term policies and permanent insurance that come with cash value growth and may give dividends. Because of this, the company can be right for people who look for low prices now, but also want to plan for the future. There is no set cost for insurance premiums. Prices change based on the insurance policy and what each person needs.
If you care about customer service, Equitable Life is a Canadian life insurance provider that you should check out. It is a good match for buyers who want help, steady support, and talks that are focused on what they need when picking life insurance options.
Empire Life is a Canadian-owned insurance company. It can be a good pick if you want affordable coverage and an easy buying experience. They offer different life insurance coverage options, like term and other longer choices. This helps people find a balance if price is important but they still want good options.
If you want to know how to get affordable life insurance in Canada, Empire Life is worth your look. Choosing the right term length, skipping extras you do not need, and comparing quotes from more than one insurance company helps keep costs low. You can add Empire Life to your list to compare.
What makes Empire Life stand out is its clear value. If you want simple choices and not too much to confuse you, this insurance company could work well for you. Empire Life is a smart choice to look at, especially if you need a budget-friendly way to protect your family and do not need extra investment add-ons.
Foresters Financial is not like many other big insurance companies. This insurance company gives you life insurance and critical illness insurance, but it also cares about the community. For some people, this idea of being a part of something matters a lot.
This company offers both life insurance and critical illness insurance. Many people also know it because it takes part in community work. Price and coverage are still important, but some people want more than just a good policy. They like a company that gives back and feels more close to its members. This can be a good thing if you want a company as your provider that feels friendly and down to earth.
Foresters Financial is not the right choice for everyone. Still, it is worth looking at when you think about buying life insurance or critical illness insurance. If you care about customer service and company values, you might want to check them out. First, make sure the cost and what they cover fit your needs. Also, think if you want a company you use online or one where you get help from an advisor.
How do you pick the right life insurance company for what you need? Begin by looking at a few key things. Check the life insurance company’s financial strength, what products they have, how much you pay, and how good their service is. The best life insurance companies will be clear about what you get, will be fair in approving you, and will give support that works with how you want to get and use your coverage.
It is also good to look at what kind of coverage options they have, not just the brand name. One Canadian insurance company might be the best fit for a young family. Another could be better if you need it for estate planning, getting no-medical life insurance, or for protecting your business. The next parts talk about the main things to check before you choose a life insurance policy.
Financial strength is very important because life insurance is a long-term promise. You want to go with an insurance company or an assurance company that will still be able to pay claims many years from now. Having a lower price does not help you if the insurance company does not have good financial strength, strong ratings, or a good history of how they work.
In Canada, you can use ratings from groups like AM Best and check LICAT ratios. The LICAT ratio compares the capital an insurer holds against the capital it is required to hold, so a ratio of 120 percent means the company has $1.20 on hand for every $1.00 required. The Office of the Superintendent of Financial Institutions, known as OSFI, sets a minimum Total Ratio of 90 percent and a minimum Core Ratio of 55 percent, plus supervisory targets of 100 percent and 70 percent that act as a cushion above those minimums. Canada's largest life insurers usually report Total Ratios comfortably above the 100 percent supervisory target.
It is also important to know who watches the insurance company, and the answer is usually more than one body. OSFI supervises the solvency of federally regulated insurers. On top of that, every insurer has to be licensed in each province where it sells, and provincial regulators such as the AMF in Quebec and FSRA in Ontario oversee market conduct and advisor licensing. So a federally regulated company answers to both levels, not one instead of the other.
Key things to check:
Not every provider has the same life insurance products, so it is important to compare what each company offers. Some companies focus more on term life, while others give strong choices for whole life, universal life insurance, and no-medical plans. When there are more options, it is easier for people to find coverage that really fits what they need.
In Canada, you will see both temporary and permanent life insurance choices. Term life is good for people who want lower-cost protection during their working years. Whole life and other permanent plans can work well for estate planning or for families who need support for a long time. They also help anyone looking for coverage that lasts their whole life and may even build cash value. If you are looking into term vs whole life insurance in Canada, this is when you start to see the real differences.
Common types of life insurance products are:
The way underwriting works can change how easy it is to get approved and what you pay for the insurance policy. Some companies ask a lot of medical questions or want you to get a medical exam. Others have term policies where you answer only a few questions or even get guaranteed issue coverage. But those plans can cost more or not offer as much.
How flexible the policy is can also be important. Some insurers will let you turn your term policies into long-term ones without needing a new medical exam. Some will have easy renewals or medical-free options if you have health worries. This can help if your needs change later or getting approved seems tough right now.
Both Canadian companies and foreign insurers selling in Canada try to offer good deals, but the main thing for you is how insurance policies are issued, what they cost, and how you are treated after you buy. It’s better to look at how flexible a policy is, how you get approved, and the service you get, not just who owns the company.
Price is what people usually notice first, but customer service is really important when you need help or when your family has to file a claim. The best life insurance companies know this. They work hard to make talking with them easy. They also make the claims process simple, fair, and fast. All of that can help lower stress at a tough time.
Some people want to do everything on the computer or phone. Others want to talk to someone on the phone or meet face-to-face. There is not just one way that is right for everyone. Life insurance companies like RBC Insurance, Sun Life, Equitable Life, and some others are often someone's first choices for good service. Still, you have to pick the insurance company and customer service style that feels right for you.
What to review:
Insurance premiums can be very different from one company to the next, even if the coverage is the same. This is why it is important to compare quotes. Some companies may give you a better price for term coverage, but other companies might have higher premiums because they offer more options or are more flexible.
Check if you can pay each month, every few months, or just once a year. This can help you plan your money better. Some providers have good deals, like first-year discounts if both people in a couple sign up, or if child coverage is already included. These things can add value to your insurance without changing the main policy.
Look for pricing details such as:
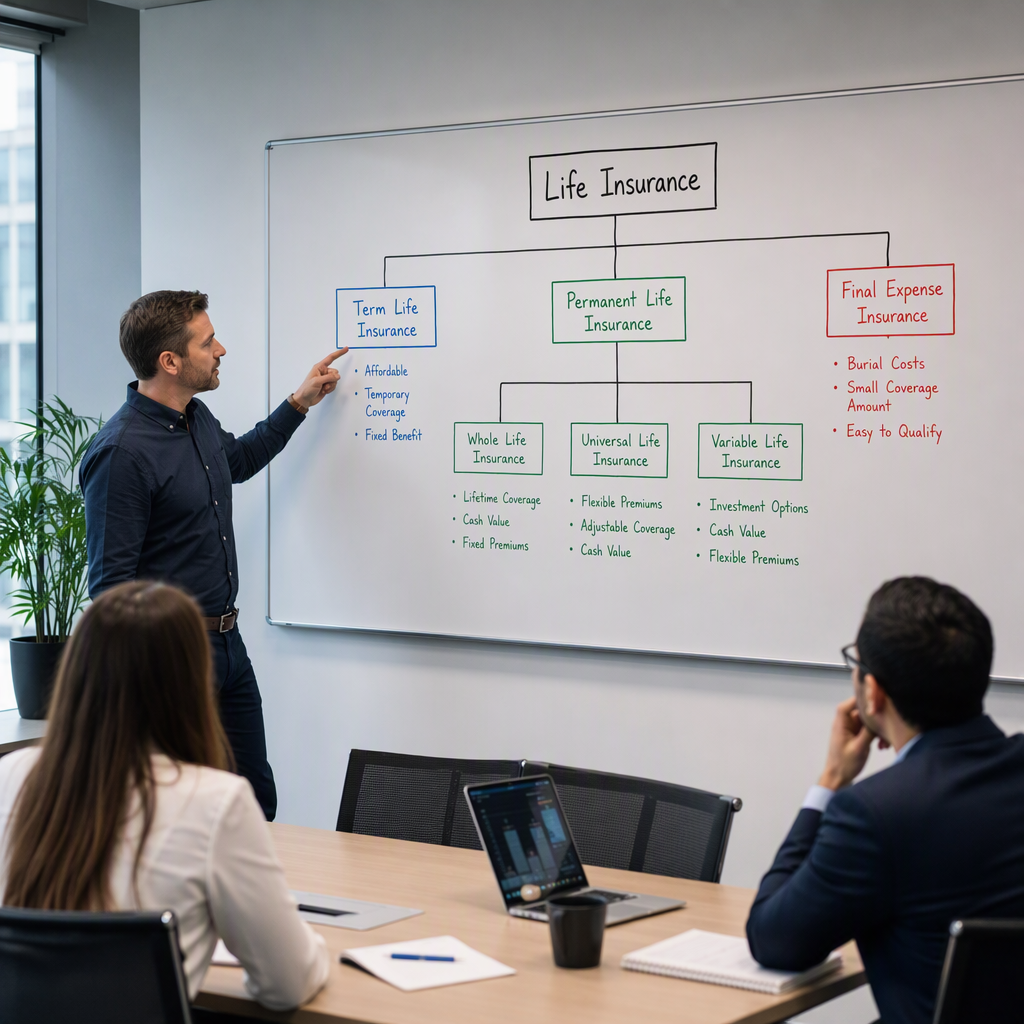
Most Canadian life insurance companies offer both term life insurance and permanent coverage. This means you will often see options like whole life insurance, universal life insurance, and sometimes group plans or those with no medical test. The choice depends on how long you want coverage. It also depends on if having cash value is important to you.
If you are looking at insurance options, keep things easy. First, think about your main goal. Do you want short-term or lifelong protection, benefits from your job, or a policy that is easy to get? The next parts explain the most common types of life insurance in Canada in a simple way.
Term life insurance is easy to understand and usually not as costly as other types. You are covered for a certain amount of time, like 10, 20, or 30 years. If you die during this time, the insurance company will pay a death benefit. For most people, term life is a good first step when they are looking at life insurance options.
This form of insurance can be a good fit when you need coverage just for a short time. You might think about years when you pay your mortgage or have childcare costs. It can help replace your income while your family needs you. People often buy term life insurance when they get new debt, get married, have kids, or start to plan for others in their life.
Term life may be a good choice for:
Whole life insurance is a kind of permanent life insurance that stays active for your whole life if you keep paying the premiums. It has fixed premiums and a cash value that grows over time. This makes it cost more than term coverage.
This plan can be good for people who want certainty and long-term coverage. It also helps with estate planning. Some whole life policies pay dividends. This depends on the insurance company and the product. If you are looking at life insurance in Canada for family needs or plans for the future, whole life insurance might help.
Whole life often gets picked by people who want:
Permanent life insurance is more than just whole life. It covers whole life plus other options like universal life. The main point is that this type of insurance policy does not end after a set time. That is not the same as temporary life insurance.
Some people buy term life insurance at first. They may later use conversion options to switch to permanent life insurance. This is good if your needs change and you want coverage for your whole life, but you do not want to take another medical exam. Many insurers and assurance company options let you do this. It gives people more ways to pick what fits for them over time.
Permanent life insurance plans can help with:
No medical life insurance policies can help people who might not get regular life insurance. The process is often faster, and you may not need to take a medical exam. Some plans ask fewer medical questions, and a few guarantee coverage without asking any questions at all.
The trade-off is that it may cost more, or you may get less coverage for the same death benefit. When you look at fully underwritten plans, no medical life insurance is often less affordable coverage for the same amount of protection. But, it can still be good for people if health issues, time limits, or the stress of sharing personal details make regular life insurance hard.
These policies may be useful for:
Group life insurance through work can help you get started. But it should not be the only way you protect yourself. Many people get life insurance coverage at their job. This is often easy to get. You may not need a medical check for it.
But it may not stay with you if you leave your job. The amount you get may not be enough for your family. This is why many people in Canada add their own life insurance coverage.
Group life insurance at work can help with:
Comparing life insurance quotes in Canada is one of the best ways to make sure you do not pay too much. Two insurance companies may give the same person very different prices, even if the main coverage is almost the same. That is why it is better to look at quotes side by side instead of just looking at one at a time.
A good look at life insurance quotes means more than just looking at price. You should also check the insurance company, the term length, if you can change your policy later, and any other things in the policy that can change how helpful it is over time. The next parts explain how to ask for life insurance quotes, what can make quotes cost more, and how online tools can help you.
Getting life insurance quotes Canada is simple when you know what you need. You should first decide how much coverage you want, how long you need it, and if term or permanent life insurance is the right choice. After that, use online tools or talk to a licensed advisor to compare different insurers at the same time.
You can find a full list of licensed providers through regulator and industry sites. But your goal should not be to quote every company. You want to focus on the best options for you. When going through the application process, you will likely have to give your age, the province you live in, if you smoke, and some basic health info.
When you compare life insurance quotes, check:
Insurance premiums are based on risk, and the biggest factor is age. Rates go up as you get older. This is why many people try to buy life insurance sooner. Health, smoking, and the way your policy is set up also change how much life insurance costs for you.
The policy type is also important. Term life insurance costs less than permanent life insurance most of the time. If you smoke, you will pay much more than someone who does not. The insurance company will also check how much life insurance you want and if your policy comes with any extras. These main ways of pricing are the same for many Canadian companies and providers from outside that sell in Canada.
Main price drivers include:
Online tools help save time when you want to compare more than one insurance company. Using a life insurance calculator can show how much coverage you may need for your debts, your income, and your family needs. Quote platforms let you look at insurance quotes without talking to every insurance company on your own.
If you want things to be even easier, PolicyNinja is a good way to compare plans from Canadian providers. You can visit https://www.policyninja.co/ and see insurance quotes in a more simple way. This helps when you want less stress and need a shortlist fast, especially if looking for a life insurance broker near me is too much.
You may find these helpful tools:
Many people look only at price when they shop for life insurance. But the cheapest insurance quotes do not always mean you get the best life insurance or the right value. Some life insurance plans can look cheap, but have weak options, bad customer service, or do not allow you to change your policy later. You do not want to get stuck with the wrong policy just to save a little each month.
It can also be a problem if you compare one insurance company to another when the details are not the same. For example, one life insurance quote could be for a 10-year term and the other is for 20 years. Prices will not match up that way. This is also true when you see different face values, policy riders, or ways the company checks your health.
To get the best life insurance, try not to make these mistakes:
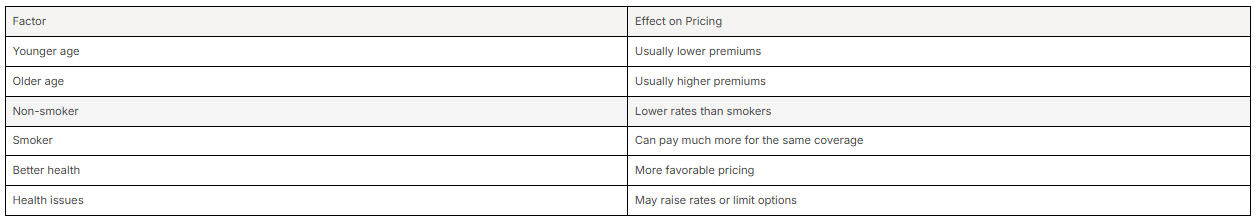
Pricing with Canadian life insurance can seem tricky, but it is easy once you know the basics. Insurance premiums depend on your risk and the policy you pick. If you are young, healthy, and do not smoke, then you will pay less. If you are older or smoke, you will pay more.
Still, the lowest price may not be the best life insurance choice. You also have to think about coverage quality, flexibility, and service along with the price. The sections that are coming up talk about how things like your age, health, policy type, and add-ons affect what you pay. They also tell you how to keep canadian life insurance affordable.
Age is usually the biggest pricing factor. In the compiled information, premiums tend to rise as applicants get older, and smokers may pay two to three times more than non-smokers. Health and lifestyle choices shape risk, so insurers use them to set insurance premiums.
Gender can also affect pricing, with sample figures showing lower rates for women in some cases. Smoking status has a major impact, especially at older ages. This is why buying earlier, while healthy, can help lock in better pricing.
Changing your policy type has a big impact on cost. Term insurance is often the most affordable coverage. This is because it only lasts for a set number of years. Whole life insurance and other permanent choices will cost more. These give lifelong protection and may also have cash value features.
The amount of coverage is important, too. As you buy more protection, you will pay more. Many people use a rule of 7 to 10 times their yearly income, but your amount should actually be based on things like your mortgage, debts, child care, and if your income needs to be replaced. This will help you decide how much life insurance you need.
If your budget is tight, some people in Canada pick a smaller amount of coverage or a shorter term. This can help you get life insurance now and keep costs down, without going over what you can afford.
Optional riders can help make a policy work better for you, but they will raise the total cost. These extras let you change your coverage to fit what your family, your health, or your business needs. Sometimes, you may want more than just a basic death benefit.
The compiled information shows that the common add-ons are child coverage, protection for critical illness, and disability insurance options. Some insurance companies also offer conversion rights or extra ways to change your policy in the future. You should pay only for what helps you reach your goals.
Useful coverage options are:
Finding affordable life insurance in Canada starts with seeing what you need from a policy. If you want easy family cover, term policies help you pay less. Buying your plan when you are younger and healthy can lower the price too.
Next, get insurance quotes from many insurers. Do not think a brand you know must give the best price. Each company can have cheaper rates for younger people, non-smokers, or some kinds of health. That is why you need to compare quotes when you want the best life insurance for your money.
To keep your coverage cost down:
Choosing between life insurance companies comes down to what you need. The best assurance company for you will depend on your age, your health, your family, how much money you want to spend, and the kind of customer service you want. One insurance company might be better if you want simple, low-cost term coverage. Another might be better if you want to plan for the long run.
To make the best choice, you should look at your options and see what works for you before you pick a life insurance company. Think about the amount of coverage that is right for you, how long you will need it, and if you need coverage for personal or business reasons. The next sections will help you make this choice about life insurance easier.
Start by thinking about your real needs. If your family needs your income, your life insurance should help replace what you make, pay off debts, and cover any future costs, like money for childcare or school. This kind of clear plan is better than guessing.
You also have to think about long-term plans. Some people only need help with a mortgage for a certain time. Others want life insurance that helps with estate planning or to keep a business running. If you run a company, you may need to know what is key person insurance, corporate owned life insurance Canada, or shareholder protection insurance Canada. These things will help you find the right provider and the right life insurance coverage.
Ask yourself:
When you pick an insurance company, there be more things to look at than just the price. Ask about things that matter to you. This helps you compare life insurance companies in Canada, so you find the one that best fits what you need. A big name in insurance does not mean it will be right for you.
Think about how you apply for life insurance, if the company is stable with good money, and what help you will get after you buy the plan. You also want to see if the provider gives you good coverage options now, and lets you change things later. This is important for families, parents, young adults, and for business owners.
You could ask questions like:
Reviews and company ratings help you know what a life insurance provider is really like behind their ads. They will not tell you everything, but you can spot trends in customer service, problems, and how easy it is to talk with them. This can help when you need to pick from your shortlist.
To check the financial strength of canadian life insurance companies, look at ratings from A.M. Best and study company info, like yearly reports and how much capital they have. To see how good their service is, look at feedback from people, find info on the Better Business Bureau, and read more reviews where you can. These steps will give you a fuller picture of a life insurance company than just the price.
Where can you look for reviews and ratings for canadian life insurance companies? Begin on the insurer websites to see details about their products. After that, use third-party ratings, the BBB, and different comparison platforms. This is a good way to check their stability and customer service before you apply for a policy.
If you want an easier way to look at Canadian life insurance options, PolicyNinja can help take some work off your hands. You do not have to jump from one insurer’s site to another. At this one spot, you can go over different insurance quotes and check the key differences with less effort.
This is good when you have to think about your age, health, budget, debts, and what you want down the road. No matter if you want family life insurance Canada, life insurance for parents Canada, or just want to see life insurance explained Canada, a comparison tool helps make it all easier.
PolicyNinja can help you:
When you compare Canadian life insurance companies, you help find the best life insurance for your family and your money needs. Knowing the different policies, plus looking at what each insurance company offers, can make this work better for you. Don't forget to think about price and customer service, since the both matter. Your age, health, and budget help pick which plan fits you the most. Take a little time to check all the details. For an easy way to pick, go to PolicyNinja and see insurance options from trusted Canadian life insurance companies. Start now, and feel good knowing you keep your family safe with the best life insurance.
Start by confirming the insurer is licensed in your province, then check whether it is federally regulated by OSFI. After that, look at its AM Best rating, its LICAT Total Ratio against OSFI's 90 percent minimum and 100 percent supervisory target, its annual reports, and its claims history. Together these tell you the financial strength and financial stability of a Canadian life insurance or assurance company before you apply.
Not every one, no. The CLHIA is a voluntary trade association, so joining is a choice rather than a requirement. In practice its members account for about 99 percent of the life and health insurance business in Canada, so nearly every company you compare will be a member. Keep in mind that membership is not the same thing as regulation. What actually protects you is that the insurer is licensed in your province and supervised by OSFI or a provincial regulator, so check that first.
The main difference is not always who owns the insurance company. When you look at each Canadian life insurance company or other foreign insurance providers in Canada, you want to check things like product range, service, how they decide to accept people, and their financial stability. The rules can be set by the federal or provincial government, but what people care about when buying stays mostly the same.
Cindy David, CFP, CLU, FEA, TEP, is President & Estate Planning Advisor at Cindy David Financial Group Ltd. in Vancouver. A recognized leader in wealth management and estate planning, Cindy guides clients with strategic, tax-effective solutions while championing innovation and women’s leadership in the financial industry. She is the former Chair of the Conference for Advanced Life Underwriting (CALU) — Canada’s professional association for senior life insurance and financial advisors that advances education, advocacy, and best practices in advanced planning and public policy.


