›

Universal life insurance Canada is talked about as a way to get both coverage and savings in one life insurance policy. That can sound good, but it may not be right for every person or each family. The best choice for you may depend on your age, how much money you can spend, your coverage amount, your health, and your goals. Some people in Canada want a universal life insurance policy to get both flexibility and coverage that lasts a long time. Others want something more simple. This guide gives you an easy way to learn about universal life insurance. With this, you can look at other options and pick what works best for you.
Some people in Canada think about getting universal life insurance when they want more than just basic life insurance coverage. They may want to be sure they have coverage for life. They may need a plan where they can change their premium payments, or pick one that can build cash value over the years. Sometimes, this helps with estate planning, business planning, and looking after their long-term financial future.
Others are interested in universal life after they talk to a financial advisor about their coverage needs. The type of policy also gets attention from people who make a lot of money, business owners, or anyone wanting a permanent life insurance Canada has that lets them invest. The next parts talk about where universal life policies can be a good fit.
Your reasons for buying life insurance can change as you get older. When you are young and make a lot of money, you might want a policy that helps with long-term plans. Parents often look for steady life insurance to help their children. If you own a business, you may want life insurance to help with your company in the future. What you need for coverage, and your money goals, will often guide your choice.
You might also think about universal life if you have already tried other plans and now want another way to save on income tax. Many people like to check it against other types like personal life insurance, family life insurance Canada options, or even term to 100 life insurance Canada plans before they decide.
Here are some common reasons people look at these plans:
The right timing is important. Most people look at universal life when they have a steady income and want to plan far ahead.
Universal life insurance can be good for people in Canada who want permanent life insurance that has more options. Some may like that you can use universal life for more than just a payout. For example, someone who has a high income and has already put the most money into a TFSA or registered retirement savings plan might use universal life for tax-deferred growth. A business owner might also need it for things like estate goals or planning for who will run the company next.
In business, people often look up things like executive life insurance Canada, corporate owned life insurance Canada, partnership life insurance Canada, and shareholder protection insurance Canada. These all relate to permanent coverage needs, like buy sell life insurance Canada or planning for business succession insurance Canada.
Possible examples of a good fit:
But, the best fit will be different for each person. It depends on things like your income, how much risk you are okay with, and if you can handle managing the policy over the years.
Universal life insurance is a type of permanent life insurance policy that has two main parts. One part pays for the cost of insurance and any administrative fees. The other part can build up cash value, depending on your premium payments and how the policy works.
With universal life insurance, you get some flexibility with your premium payments, but you still need to have enough money in the policy so it stays active. If the cash value does not do well and your payments are too low, the life insurance policy can end. This is why you need to look at both the insurance side and the investment side of your universal life.
The insurance part is what gives you the main protection. If you die while your life insurance policy is still active, the insurance company will pay a death benefit to your loved ones. They get a lump sum of money. In most cases, your family or people you choose will not pay tax on this money. They can use it to help with the family, the house, or even a business.
You pick how much coverage amount you want when you buy the policy. In some cases, you can change this amount later. If you want to get more life insurance coverage later, the insurance company may want you to take a medical exam. If you decide to lower your coverage, the cost or premium may go down, too.
That is why universal life is mainly about giving life insurance first. Some people talk a lot about the investment side, but the main goal is still protection. Universal life can help with life insurance beneficiary rules Canada, help keep your family safe, and support life insurance benefits Canada. The important thing is to keep the policy active and paid up.
The second part is about how universal life works with investments. When you pay the premium, some of it goes into an investment account. Over time, this helps your policy build cash value. People call universal life “cash value life insurance” because of this feature. While your money is inside the policy, the growth is tax-deferred.
With universal life, you can pick from different investment options. The choices depend on the insurer. They may include fixed-rate accounts, index-linked accounts, or even a few options that act like variable investments. This can give you more ways to try to grow the money, but it can also make things more risky and harder to follow, especially compared to whole life insurance.
When the policy’s cash value goes up, you can borrow money from it or take some out. But, sometimes investment returns are not as high as you hope, and fees can also lower how much you get. If the investment account does not do well for a long time, you might have to put in more money yourself just to keep your coverage.
A universal life insurance policy is different because it gives both protection and more freedom. With this type of policy, you can get lifetime coverage. You can also change how much you pay for your premium. There is a cash value account, and you can pick from a few investment options. That is why some people in Canada look at universal life insurance policy like both whole life and term coverage.
But these features matter only if they fit your own needs. A policy with a lot going on is not always better. If you want to see if a flexible life insurance Canada plan is right for you, think about the way premiums, coverage, and taxes will work each day. This can make it easier for you to pick the life insurance policy that gives you what you need.
One of the top things people like is flexibility. Universal life has the option for you to make premium payments that are more than the lowest needed. This can help build up more cash value. Sometimes, if there is enough value in there, the policy can even cover some of its own costs for a bit.
This sounds good, but flexible premiums still come with rules. The policy must always have enough money to take care of the cost of insurance and any fees. If you pay too little for too long, you could run low on money. When that happens, the whole universal life policy could end.
Being able to change your coverage amount helps when life is different. If you owe less or your needs drop, you can try to lower your coverage amount. If you want more protection, you may (later) ask for higher coverage. But to get increases, you may need a medical exam or more checks. So, there is flexibility, but to get the most from it, you need to watch your policy and manage it well.
Tax is one reason some people look at universal life insurance. The cash value in these policies can grow without being taxed each year, as long as the money stays in the policy. The death benefit is usually paid to the people you choose without any income tax.
But these tax advantages do not always mean your money is tax-free in every case. If you make withdrawals, you can face tax implications. Giving up the policy, or surrendering it, might also bring up income tax. The Income Tax Act has rules that limit how much money you can add before you lose these good tax advantages.
People talk about policy loans as well. Sometimes, taking a loan from your policy does not cause taxes right away. But you could have to pay interest, and if you do not pay back what you borrow, the amount your loved ones get for the death benefit can go down. If you want to buy universal life insurance mostly for tax planning, you should get advice so you know what works for you.
Universal life insurance can give real value if you are in the right spot. The best thing about this is it gives lifetime coverage and comes with a cash value account that is tax-deferred. For some people in Canada, this blend of lifetime coverage and cash value is better for planning long-term things than getting coverage for just a short time.
This type of permanent life insurance may help to give you more financial security if you are looking for protection that changes as your needs change. The death benefit can give support to your family or loved ones when you are gone, and the policy can fit in with your plans for your estate or your business. The next two parts will talk more about how these things help in day-to-day life.
One big benefit of universal life is that it gives you permanent life insurance. As long as you keep adding money to the policy, it will not end after 10, 20, or 30 years like term coverage does. This can be good if you want coverage that lasts your whole life, no matter when you die.
Universal life can help you make sure you leave a set amount of money for your family, cover final bills, or give help to loved ones as they get older. For many people, that kind of lifelong support helps build a stable financial future and gives peace of mind.
But this only works if you keep up with the payments for the policy. Having lifetime coverage is not the same as getting coverage no matter what. If you do not pay enough, or if the cash value runs out, the policy could end. So, the promise of lasting coverage with universal life depends on making sure you keep it active and check on it often.
Universal life insurance comes up a lot in estate planning and business planning. People talk about it because it gives a lasting death benefit and has features that help with taxes. You may use universal life to help pay taxes, move your money to others, or help keep your business running. This is why some people want more than just basic coverage.
If you own a business, you might want to know what is key person insurance, buy sell agreement insurance Canada, how does buy sell insurance work, business continuation insurance Canada, and affordable business insurance Canada. When you need permanent life insurance coverage, universal life can play a part in those plans.
Here are some ways it can be used:
Universal life can work well, but only if the way the policy is set up matches what you want to do.
Universal life insurance costs more than term life. Sometimes, the early premium seems easy to handle, but you end up with more costs later. You pay for the cost of insurance, administrative fees, and you also add money to the cash value part of the plan. Because of this, you should look over any new policy very closely before you make a choice.
Monthly premiums in universal life insurance can change. This sounds like a good thing, but that freedom can cause problems down the road. If the investment part does not do well, or if you do not put in enough money, you may need to pay more in the future. So, when you look at the price, also think about the risk that comes with it. Do not just look at price alone.
The price of universal life insurance in Canada changes for each person. It depends on things like your age, if you are male or female, if you smoke, your health, and the amount of coverage you pick. Some universal life plans also cost more as you get older, because the inside costs from the insurance company can go up over time.
The insurance company you choose and how they build the product also matter. If you want a policy with more options to invest, extra features, or a bigger death benefit, it will cost more money. If you decide to cancel your policy, you may get less back. That is because surrender charges and taxes take away some of the cash value.
Here are some common things that change the cost of insurance:
This is why it is a good idea to compare life insurance quotes Canada side by side before you choose.
Cost is one of the clearest differences between these three policy types. Term life usually has the lowest monthly premiums because coverage lasts for a set period only. Whole life tends to cost more, but premiums are usually fixed and cash value growth is more predictable.
Universal life sits in the middle in some cases, but not always. It can start lower than whole life, yet future funding needs may rise. That makes it harder to judge by price alone. If you are comparing term vs whole life insurance Canada or term vs universal life insurance, look past the first quote.
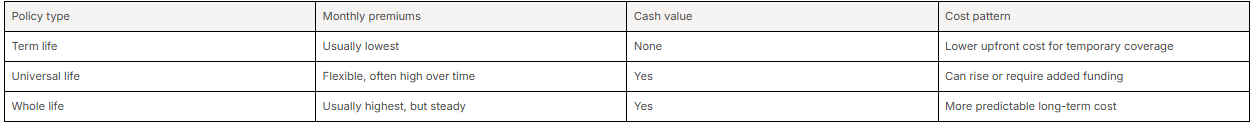
There are three types of life insurance. These are term life insurance, whole life insurance, and universal life insurance. All of them can provide a death benefit. Universal life mixes life insurance and some investment options. Whole life insurance gives you lifelong coverage, and you get steady cash value growth. Term life insurance is simple. It gives you protection for a certain number of years.
So, which one should you pick? There is not one answer that fits everyone. The best choice depends on your age, your health, your money, how much risk you want to take, and what you want the policy for. First, let’s look at whole life vs universal life insurance, and then we will compare term vs universal life insurance.
Whole life insurance and universal life insurance both give you lifetime coverage, but they do not work the same way. Whole life insurance is usually more simple and steady. You pay set premiums, and the cash value grows in a way the insurance company guarantees. Universal life insurance gives you more say in some things, but that also means you have more to do.
In universal life insurance, the investment components can go up or down based on what you choose. This gives flexibility, but there can be problems if things don’t turn out well or if there is not enough money put in. If you do not want to watch your policy often, whole life insurance may be easier for you.
Key differences include:
This is what to know when picking between whole life and universal life insurance.
If you want low-cost coverage for things like a mortgage, kids, or needs that last for a set time, term life insurance is often the better option. It is simple, easy to get, and costs less. Many families use term life insurance to protect their income during the years when they have the most to look after.
Universal life insurance may work better if you want lifelong coverage, can pay the higher cost of insurance, and feel good about handling a policy that has more parts to keep track of. It can also help with estate or business planning. But universal life is not always the best for every family.
Term life insurance may work best if you want:
That is why many Canadians use life insurance explained Canada resources to compare different options before they pick the right one for their needs.
To sum it up, universal life insurance gives Canadian families both coverage and ways to grow their money. When you know how universal life policies work, you get to fit the coverage around your changing needs. This can also help you reach long-term money goals. You can use universal life to plan for your estate, protect your work or your business, or help keep your loved ones safe. This kind of life insurance is flexible and lasts for a long time. But it is important to look at your own life and needs first to see if universal life insurance is the right one for you. Want to check your options for universal life? You can get a quote and see different policies fast with PolicyNinja, so you find the one that is right for you.
Most people in Canada do not start with universal life insurance. This type of life insurance may be good for those who want lifetime coverage and have some long-term goals. But many families just need simple coverage to keep them safe. A financial advisor can look at your coverage needs and help you choose a life insurance plan that fits well with your financial security.
Yes, a universal life policy lets you change your coverage and make flexible premium payments. But, the insurance company still needs you to have enough amount of money in the policy to pay all costs. If you later want to add more coverage, you may have to do more underwriting or have a medical check.
Yes, there can be tax advantages. Money in a universal life insurance investment account can grow without paying taxes right away. The death benefit, in most cases, is paid out tax-free. But if you take money out, end the policy, or go over funding limits set by the Income Tax Act, there can be tax implications. So, it is important to know all the details when you have a life insurance policy like universal life.
A lot of people buy universal life insurance without really knowing why. Some people also pick universal life when a better option could fit their coverage needs. If your investment strategy is not strong, or if you stop the policy early, there can be fees and surrender charges that lower what you get from the life insurance.
Problems can happen with a universal life policy if the coverage amount is higher than what you can pay for, or if there is not enough money to cover the cost of insurance and administrative fees. If the cash value of your policy does not grow enough to handle those ongoing charges, your coverage may not last as long as you want.
Many people think about how flexible a life insurance policy is but do not see the risk. A universal life insurance policy does give you a lot of investment options. Still, bad choices for your investment options will make it hard for your money to grow. It is important to have a good investment strategy because policy loans will lower what you get back from your universal life insurance policy later. Some types of universal life insurance also use market value adjustments or other rules that can change what you be paid.
Universal life insurance can be good for people who make a lot of money, business owners, or those who have special goals for passing things on after they die. This type of insurance may not work well for someone who wants a basic plan or does not have much extra cash to spend. A financial advisor can help you see if your coverage needs make spending this amount of money on universal life insurance the right choice for you.
People who get the most out of universal life insurance often want lifetime coverage. They care about their long-term planning. This can mean they want help with estate planning, making sure their business keeps going, or knowing there will be a set coverage amount left behind. Universal life can be a good part of your financial future plan, especially when other life insurance choices do not give you what you need.
If you want life insurance that is easy to understand and does not need you to manage it, a simpler policy might be the better option. Term insurance can work well for short-term needs. If you want permanent life insurance and do not want to make investment choices, whole life can be easier than getting a brand new policy that is complex. With straightforward life insurance coverage, you will know what you get.
When you want to compare universal life insurance, you need to look at more than only the price. Be sure to look at the life insurance company, their costs, how you can pay, and how the coverage amount might change. Compare universal life with other types of life insurance too. It is good to ask a financial advisor for help before you pick one.
Begin by looking at the coverage amount and how much the insurer charges. Next, see what the administrative fees are and if there is a funding minimum. Check how the policy’s cash value can go up over time. You should also know the medical rules and what you can or cannot change in the plan. If what you get seems hard to understand, ask a financial advisor to help you know the trade-offs.
PolicyNinja lets you look at your options from different insurance company choices in one spot. This helps you focus on what matches your coverage needs. You do not need to guess which is the better option for you. You can see all the choices clearly. Visit https://www.policyninja.co/ for a simple way to compare what you need.
If you want to learn more about universal life insurance, start by seeing how each policy fits your goals. Don’t just go by what someone says. Think about the investment options, how you have to fund the plan, and the coverage amount you need. Then, see how this matches up with other types of life insurance. Also, think about what role coverage will play in your own financial future.
You can get a fast quote to help make things easier. When you use PolicyNinja, you get to compare life insurance providers. You also can look at your coverage amount and see what you need. This helps you decide if a universal life insurance plan or a new policy is good for you. It is a good way to find the right life insurance company for you.
Before you apply for a life insurance policy, stop and think about a few easy things. Ask yourself how the policy fits your budget and your life. You can also talk with a financial advisor if you want help. This step can make your coverage needs more clear.
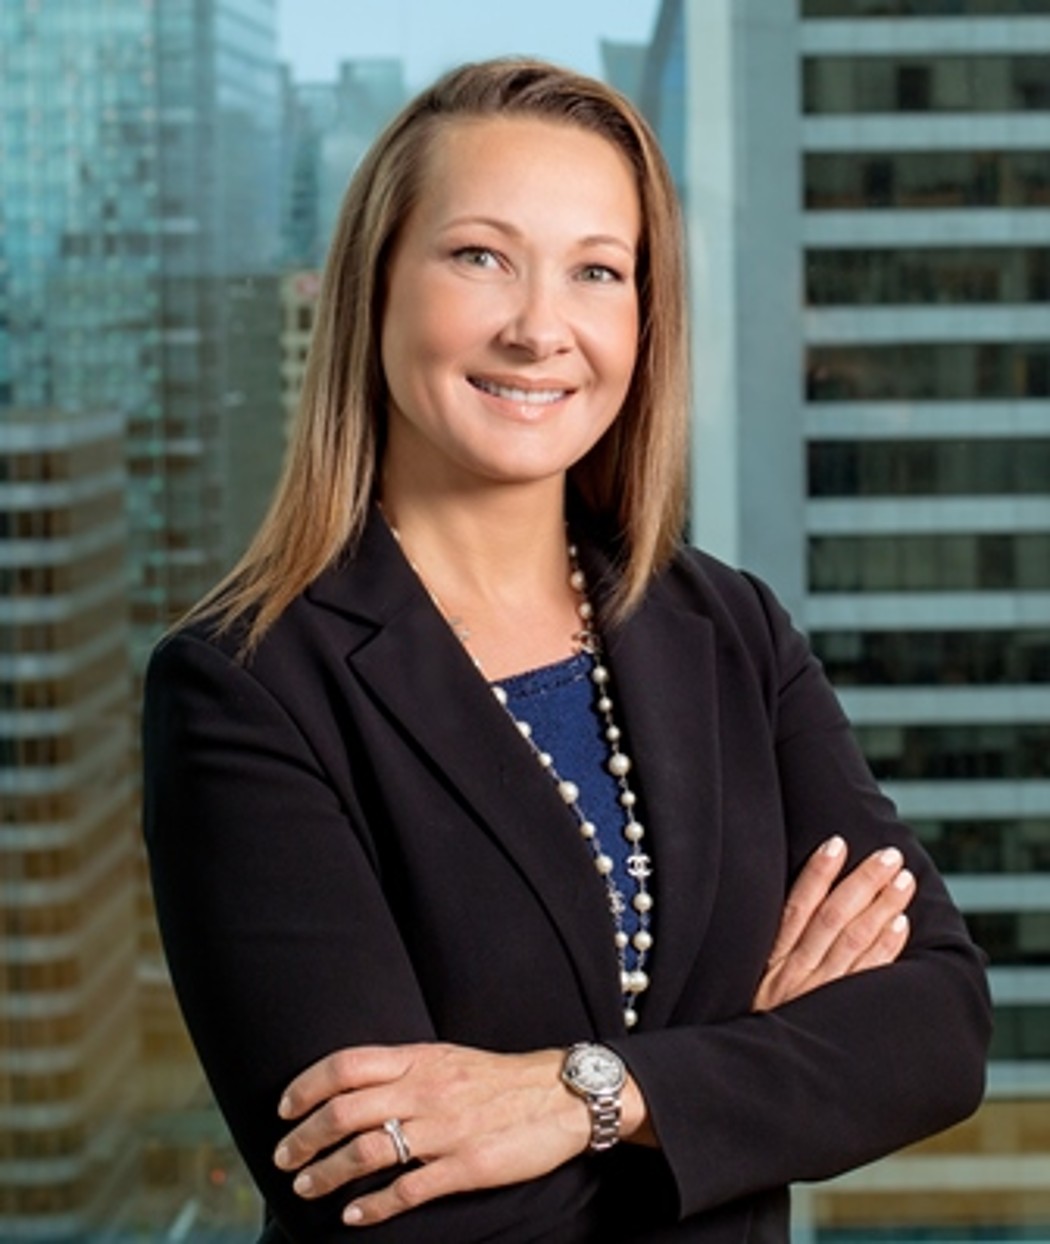
Cindy David, CFP, CLU, FEA, TEP, is President & Estate Planning Advisor at Cindy David Financial Group Ltd. in Vancouver. A recognized leader in wealth management and estate planning, Cindy guides clients with strategic, tax-effective solutions while championing innovation and women’s leadership in the financial industry. She is the former Chair of the Conference for Advanced Life Underwriting (CALU) — Canada’s professional association for senior life insurance and financial advisors that advances education, advocacy, and best practices in advanced planning and public policy.


