›

Getting life insurance might seem like a lot at first. But asking for a quote is a simple way to start. If you want to get a life insurance quote in Canada that matches your needs and what you want to spend, it helps to know how quotes work first.
A good quote can show you what term life insurance, permanent options, and different life insurance coverage levels might cost. Then, you can look at all the plans and pick one that’s good for you and your family.
Life insurance quotes in Canada are price ideas based on the details you give. Insurance companies use your basic info and what coverage you need to show what you may pay for a life insurance policy.
You can often start the application process online, even for term life insurance. Most times, you can look at choices before you talk with anyone. If you want help with sorting options from different insurance companies, a platform like PolicyNinja can make the process easier and faster to understand.
A life insurance quote gives you an idea of how much you might pay for a policy. The quote is based on information you fill in. It’s not the final price. It gives you somewhere to start before you begin the full application process.
The quote links your profile to the amount you could pay and what the death benefit might be. You can ask for a quote for term life, whole life, or universal life insurance. The quote lets you see if the coverage fits your cost limits and your financial goals.
Online quote tools for life insurance can help. The tools work well when your answers are right and up to date. If your health or habits change when the company checks things during underwriting, the premium may change. Some sites work with advertising partners. So what you want is to look at the details of your coverage, not just the first price you see.
Life insurance quotes come from looking at your risk. The company uses your personal information to guess how likely it is that they will have to pay the death benefit while your life insurance policy is active.
A few things can change how much you pay for a term life insurance policy or a plan that lasts your whole life. When the risk is bigger, the cost is usually higher. If you pick a bigger coverage amount, you will also pay more money.
To ask for a quote, you will need to give some basic personal information. You also need to say what kind of coverage you want. This helps the company or the tool give you a better estimate at the start of the application process.
When you ask for a quote, you will need to fill in a few important things. If you have health issues from before, you can still ask for a quote online. Sometimes, you may see options that are more simple or options where you will get covered right away, but these can cost more.
If you are not sure how to answer a question, insurance advisors are there to help you. It’s good to give honest answers. This can make it easier for the company to look at your case the right way and help stop surprises later in the process.
The cost of a quote is set by the level of risk that insurance companies see in your profile. They use your personal information, the coverage amount you pick, and the details of your policy to figure out prices.
Some people will get lower rates. Others will pay higher premiums because of age, health, smoking, or risk at work. A medical exam can also change the result. The main factors below explain why two people who ask for the same coverage amount can get very different quotes.
Age and health play a big part in how much you pay for life insurance. Most of the time, people who are younger get lower rates. They are seen as less risky, so they pay less money. This is one reason why many choose to buy life insurance early, not later.
Health is important too. If you have had a sickness before, have health problems now, or some in your family do, your costs may go up. Some people need a medical exam before getting life insurance. Others can get no-exam plans, but prices may change for those. If you have health problems, there are still medical life insurance plans you can get.
The company giving you life insurance wants to know the risk. They look at how likely it is they will pay out a death benefit during the time of your policy, or over your whole life. This is why they check your age, health, and how much coverage amount you want. Good health can give you lower rates. But the real price you get is decided after they do their checks. The quote is not the last step.
Smoking, your job, and what you do each day can make your quote for term life insurance go up. Insurers pay close attention to nicotine products, because tobacco use may be linked to higher health problems. Even if you use them now and then, it can matter.
Your job can affect your price for life insurance. If you work in a job where there is danger, travel, or risk, your costs may be higher. How you live, and the choices you make, can change how much coverage is right for your coverage needs. These may suggest more risk of getting hurt or sick during the term length you pick.
These things will not always stop you from getting life insurance. They just help insurers use your risk to set a fair price for your term life.
The coverage amount and the length of your policy both affect how much you pay. If you choose a higher death benefit, you will pay more. A longer term will also cost extra since the insurer covers you for more years.
How much life insurance do you need? Start by looking at your financial needs. Add up debts, mortgage payments, costs for your children’s education, income replacement, and final expenses. Take away any coverage you already have, like group benefits from work. This is close to the DIME method that many people in Canada use to figure out how much life insurance to get.
For lots of people, term life is a good choice if you need protection for a certain time, like while you pay your mortgage or your kids depend on you. Check the coverage amount from time to time. Inflation may change what your family needs later.
When you compare quotes, you will see that there are three main types of life insurance coverage. These types are term insurance, whole life, and universal life. Each type is made for different people, plans, and money needs.
Term insurance is often the easiest choice for short-term needs. Whole life and other permanent life insurance products give you lifelong coverage. They can also help build cash value. Some people will get critical illness insurance or other add-ons. These extra options make their life insurance protection stronger. The next parts will help you look at types of life insurance and see how they work for you.
Term life insurance gives you coverage for a set number of years. Term length can be short or much longer. If you die while covered, the insurer will pay the death benefit to your chosen person.
People pick this type of life insurance when they need money protection for a short time. This can help pay a mortgage, replace lost pay, or help kids while they still need you. Many in Canada start with term life when looking for family life insurance Canada because it costs less than other types.
If you compare one term life insurance company to another, price should not be your only reason to choose. Look at renewal terms, ways to change the policy, and other facts about the coverage too.
Whole life insurance is a type of permanent life insurance. This kind lasts for your whole life as long as you keep paying the premiums. It has a death benefit that is guaranteed. It can also build cash value inside the policy over time.
The cash value in your policy will grow as the years go by. You might be able to use this cash value while you are still alive. This gives some people more options. Others see it as a way to help with long-term planning. Because the insurer will have to pay out the death benefit for sure, whole life insurance is usually more costly than term coverage.
This kind of policy is good for people who want to leave their loved ones a lump sum no matter when they die. It also works for estate planning or for anyone who wants a policy that will not end after a number of years. If you are thinking about term and whole life or other life insurance choices in Canada, focus on whether your need is only for a short time or for life. Thinking about this can help you, not just about the premium cost.
Universal life insurance is a kind of permanent policy. It gives you lifelong coverage and also has a cash value part. This cash value can help you reach some of your financial goals over time.
People talk about this type of policy when they do estate planning or tax planning. It can be a little more hands-on and harder to understand than other simple insurance policies. That is why it is important to have universal life insurance explained clearly before you get it. A lot of Canadians find it helpful to know their basic needs first. Then, they can see if they want the extra choice and options, and if they are okay with the extra cost.
Most people may want to look at other ways to save money before using life insurance as a way to invest. Advice from experts notes that accounts like TFSAs and RRSPs often give better tax benefits and let you adjust more. Universal life insurance can be useful, but it should fit a solid long-term goal.
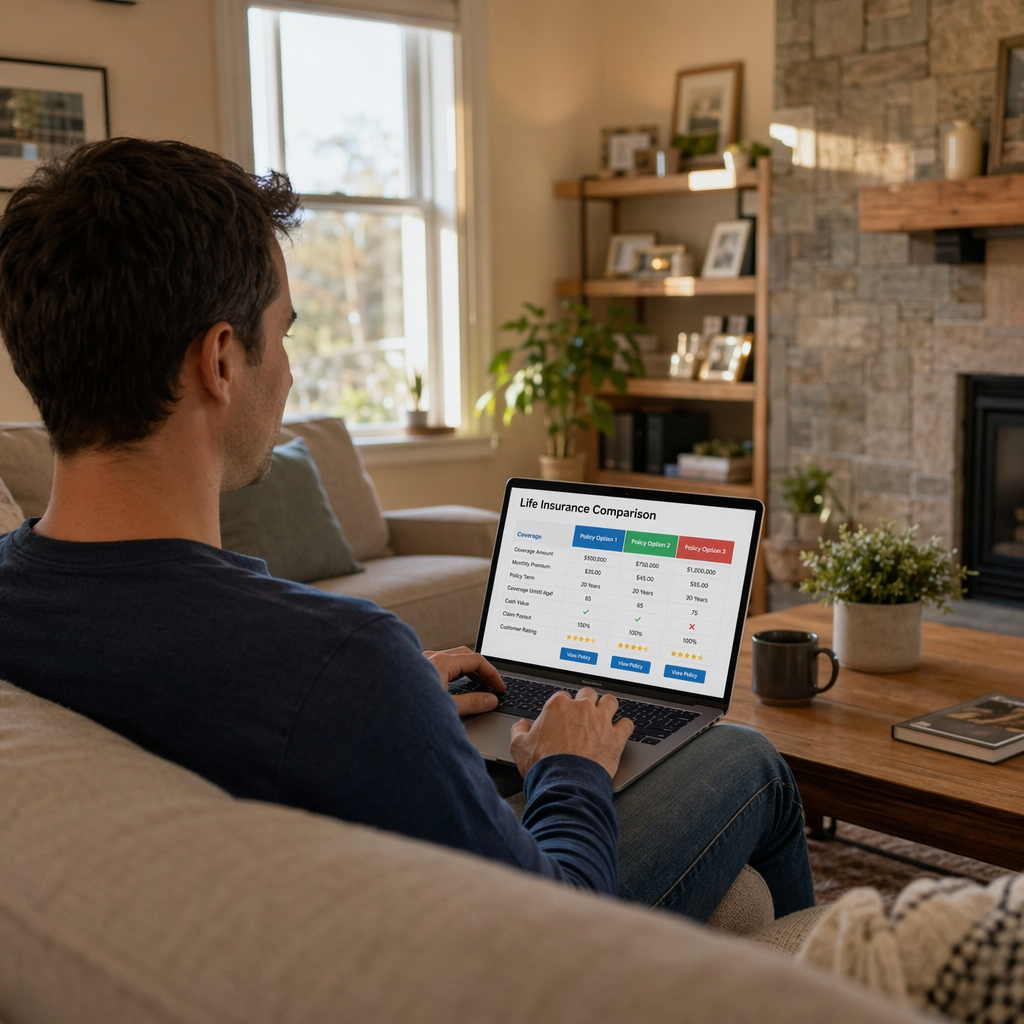
The fastest way to compare life insurance quotes in Canada is to use PolicyNinja. PolicyNinja allows you to review coverage options from multiple Canadian insurers in one place, helping you save time and compare premiums, policy terms, renewal conditions, and coverage details more easily.
But, you should keep your coverage needs the same in every life insurance quote you check. Use a life insurance calculator to get a quick idea of what you need. Still, the right way to check the quotes is to look at the policy type, term length, renewal rules, and if they need any medical info from you. The next parts will show you how to compare life insurance quotes in a simple way, so the process does not feel hard.
PolicyNinja provides an easy way to compare life insurance quotes online in Canada. You can explore available policies, review estimated costs, and identify options that suit your family, financial goals, and budget.
When comparing quotes through PolicyNinja, pay attention to:
PolicyNinja makes the comparison process clearer by bringing relevant insurance options together and giving you access to professional support. Visit PolicyNinja.co to compare life insurance quotes and find coverage that fits your needs.
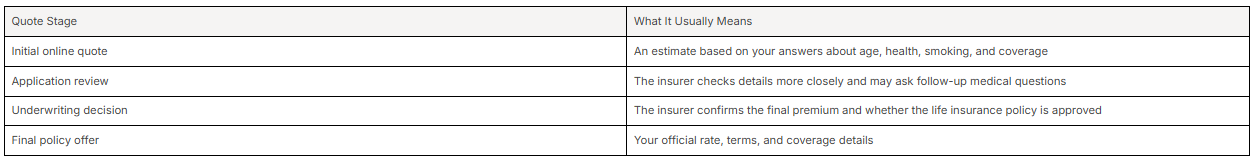
Online life insurance quotes in Canada can be accurate and reliable as a starting estimate, but they are not final. The quote depends on the relevant information you provide and may change later during underwriting.
That means online quotes are useful for research, planning, and comparing policies. They are especially helpful if you want to explore options before a full application process. Even with pre-existing conditions, you can still request a quote online. You may just need to answer more medical questions or review different product types.
Do not confuse polished marketing or the effectiveness of our advertising campaigns language on websites with guaranteed approval. A quote is a guide, not a promise.
To compare life insurance quotes in the best way, make sure you use the same details each time you ask. Keep your age, type of policy, term, and coverage amount the same. This helps you get a clearer picture when you look at the different options.
Price is important, but don't let it be the only thing you look at. You also need a plan that matches your financial goals and the amount of term life insurance coverage you need. Sometimes, the cheapest life insurance quote can hide extra rules or limits you might not see right away.
You may find guided help is useful when making your choice. PolicyNinja offers quotes from many companies and can help you understand what all those numbers mean.
If there are people who count on you for money, you should think about getting life insurance quotes. This is true for parents, people in a couple, those who own a home, and business owners. Even if you are single, you may want life insurance if you have debts or if you are making plans for the future.
Life insurance coverage is not the same for everyone. What you need will be based on your income, your debts, your family plans, and what you want your death benefit to do. If you are trying to decide how much coverage you need, think first about who will lose money if you are not around.
Parents and couples are some of the people who often need life insurance quotes. If you have someone counting on your income or your money plans together, you should think about getting coverage. Life insurance helps keep your family safe if something happens to you.
For parents, life insurance coverage can help pay for income replacement, mortgage payments, or their children’s education costs. Couples use this to make sure a partner can handle debt, rent, or day-to-day bills. That is why people in Canada search for life insurance for parents so often. The need is real and easy to see.
Term insurance can be a good choice when children are young or if you have high debts. If you are thinking about how much life insurance coverage you need, add up your household expenses, big debts, planned costs for children’s education, and final expenses. Be sure to check this number against any life insurance you get at work.
Homeowners and business owners have big money matters that don't go away after someone passes. A life insurance policy can help their family, partners, or the business deal with these bills.
If you own a house, coverage can be used to pay what is left on your mortgage and any last costs. If you run a company, your life insurance plan might help make sure the business keeps running. You may hear words like executive life insurance Canada, corporate owned life insurance Canada, partnership life insurance Canada, or shareholder protection insurance Canada during a review of your quote.
If you are an entrepreneur, you may want to learn about affordable business insurance Canada, business insurance for entrepreneurs Canada, business overhead insurance Canada, and business continuation insurance Canada. These fit into the wider talk about protection.
Self-employed Canadians should look over quotes for term life insurance because they usually do not have group life insurance through work. If you earn enough to help your family, you may need term life insurance coverage to cover all protection.
Canadians with group benefits at work should still check personal life insurance policy options. Group life insurance is helpful, but it is often limited and may end when you leave your job. That means the total life insurance coverage you get may not be much coverage if you count things like mortgage, kids, and other long-term needs.
After you get an online quote for term life, you pick a policy, fill out the application, answer any health questions, and wait for underwriting. If your term life insurance policy is approved, you check the final offer and decide if you want to accept it. Some people also look at a permanent life insurance or permanent life insurance policy if they want life insurance coverage that lasts all through their lives past work benefits.
The right life insurance policy is about what you want it to do for you. Most people match the policy to their goal, budget, and time they need it for. It is not always about getting the lowest monthly price.
To start, decide if you need life insurance for just a while or for your whole life. Think about coverage amount, term length, and if cash value is something you want. The next parts will help you compare term life insurance and permanent policy choices. It is an easy and clear way to look at what works best for you.
If you need coverage for only a set time, term life insurance is often the best choice. If you want insurance for your whole life, you may want to look at whole life insurance or another permanent life insurance option.
The main thing that sets them apart is how long they last and how they work. Term life ends after the time you pick unless you renew it or change it. Whole life insurance keeps going for your whole life and can build cash value. That is why people make term vs whole life insurance Canada comparisons a lot. They are made to meet different needs.
You may also hear about term to 100 life insurance Canada options. These give protection for a long time but are not like regular term insurance.
A good coverage amount is how much life insurance you need to take care of the people or things you are responsible for if you are not there. This amount should match your financial needs, not just what you think you can pay for right now.
First, look at all your debts, the rest of your mortgage, any help you want to give to your dependants, and final expenses. You also need to think about income replacement, so your family has money to live for the years they need help. If you have life insurance at work, you should count that in too when you decide how much life insurance you need to buy for yourself.
There isn't one amount that fits everyone. Some reports say the average household coverage in Canada was $509,000, but that number might be more or less than what you need. If you choose more coverage, it will likely cost more. That is why you need to think about both your budget and protection when picking your life insurance plan. The aim is to make sure you have enough coverage amount for your own financial needs and final expenses.
Before you pick a policy, make sure you read the fine print. The first price you see each month may seem good, but things like what is not covered, renewal rates, and extra features can have a bigger impact on how helpful it is for you in the long run.
This is also where you find out what may happen in the future. Some term policies can cost much more when you renew them. Others can give you ways to change your policy or add extras that let you be more flexible. Extra products, like critical illness insurance, help build your full plan for financial protection.
Most of the time, asking for quotes does not touch your credit score. Still, use good and relevant information with each request. Do not think all websites from advertising partners show the same details about the policy.
To sum up, getting life insurance quotes in Canada can be hard at first. But if you know how the process works, it will help you feel confident when picking a plan. Gather important details and look at different coverage options. This way, you can find a policy that fits you.
Remember, the right life insurance helps your family with money, and also gives you peace of mind. For an easier process, go to PolicyNinja to compare quotes and get advice from experts. Don’t wait, ask for your life insurance quote today on PolicyNinja and start to protect your future.
A life insurance quote in Canada is often free. Insurance companies and comparison sites usually don't ask you to pay to see a cost estimate. The price you get will be based on your age, health, coverage amount, and what type of policy you go for, like term life insurance. You should know that websites with advertising partners might show options in a different way.
No, you usually do not need a medical exam to ask for a quote. Many tools begin with simple medical questions and some other details. When you start the application process, the insurer might later ask for a medical exam. This depends on the term life insurance policy and how much life insurance coverage you want.
No, getting life insurance quotes does not usually change your credit score. It is not the same as applying for a credit card. When you use an online account, a broker, or third party sites, asking for life insurance quotes is just to get info. It is not for lending decisions.
Cindy David, CFP, CLU, FEA, TEP, is President & Estate Planning Advisor at Cindy David Financial Group Ltd. in Vancouver. A recognized leader in wealth management and estate planning, Cindy guides clients with strategic, tax-effective solutions while championing innovation and women’s leadership in the financial industry. She is the former Chair of the Conference for Advanced Life Underwriting (CALU) — Canada’s professional association for senior life insurance and financial advisors that advances education, advocacy, and best practices in advanced planning and public policy.


