›

If you have asked how life insurance works in Canada, here's the simple answer. You buy an insurance policy. You pay premiums for it. If you pass away while the policy is active, your chosen person can get money from the policy. That money can help cover bills, funeral costs, lost income, or pay off a mortgage. The best coverage amount is the one that fits your life, not someone else's. This guide shows how life insurance works in Canada in an easy way.
Life insurance in Canada is a deal the person makes with an insurance company. The person gives the company money through regular payments to keep insurance coverage. If the person dies while the policy is active, the insurance company promises to pay out a death benefit.
This payment usually goes to the chosen people (beneficiaries). They get it as a tax-free lump sum. So, life insurance is all about paying now, and having your family get financial protection from a free lump sum later. The steps to get this are explained in the next sections.
Here is how a life insurance policy works from beginning to end. You apply for the insurance. Then the insurer looks at your details. If you agree to the offer, you pay to start your insurance coverage.
The usual steps are:
After this, your policy stays active if you do what the rules say. If you die while your insurance is still active, your beneficiary can make a claim. The insurer checks the papers. If everything is fine, the death benefit will be paid. That is what happens and how life insurance works in Canada.
There are three key people in every policy. The policyholder is the one who owns the contract. The insured person is the one whose death leads to the death benefit payout. Sometimes, the same person may be both the policyholder and the insured, but in some cases, they are not.
Beneficiaries are those who get the death benefit. It can be a person, trust, charity, or even an estate. You can choose one or many people to get the death benefit. You can pick main beneficiaries and also list backups. This is important because the insurance company will pay based on the names listed in the policy.
If you want to follow life insurance beneficiary rules in Canada, it is good to keep those names up to date. Things like marriage, divorce, having children, or the death of a beneficiary are times for you to check the policy. If one of your beneficiaries is a minor, you should name a trustee or administrator so they can get the money for the minor.
Coverage is the amount your policy will pay if a claim gets approved. In life insurance in Canada, people often call this the coverage amount or death benefit. This money gives financial protection to your family.
That money can help with things like:
Your insurance coverage needs to fit your real life. Some Canadians want just enough for final expenses. Others need much coverage if they have kids, a mortgage, or someone in their life who counts on their income. A good idea is to add up what you need, then take away any savings or workplace insurance coverage you have.

Not every Canadian needs the same life insurance policy, but many should think about getting coverage. If you die and the people you leave behind get stuck with financial obligations, lost income, or outstanding debts, life insurance can help.
Parents, spouses, homeowners, business owners, or even people who have retired and have dependents may want to get this kind of financial protection. The life insurance Canada needs can change as your life changes, so it's a good idea to look at why people buy it, and know when you should check your coverage.
Many people in Canada buy life insurance to help their family if they pass away. The main aim is not to make extra money. It is to take away some of the stress from those left behind.
Common reasons are:
Term life is often good for needs that last a short time, like raising kids or paying off your home. Permanent life insurance works well for needs that stay your whole life, such as final expenses or estate planning. Life insurance for parents Canada and life insurance for young adults Canada each can be smart, but they are right for different reasons and budgets.
Keywords: permanent life insurance, term life, life insurance, estate planning, lost income, funeral costs, final expenses, children’s education
The right life insurance policy for you depends on your specific situation. Your age matters, because the cost of premiums usually goes up as you get older. What you have to do for your family is important, too, especially if you have family members who count on your income or care.
Think about:
The coverage amount should match what your household would need. That is why people often ask “when to buy life insurance” after major life events, such as marriage, having a child, or buying a home. The best policy is the one that fits your family and your life, not just any rule.
Life insurance should not be set once and left without checking. Your insurance needs can change when your income, debts, or family grows. A policy that worked well in the past may not be right now.
Marriage, divorce, having a child, buying a home, changing jobs, or getting into big debt are good times to review your policy. You could need more coverage, less coverage, or a different term. If you leave a job, your workplace insurance can change too.
Having a regular look at your policy helps keep your financial plan going the right way. If you want to know how much coverage is enough, compare options to help you choose. Many Canadians compare life insurance Canada quotes before making changes.
Applying is usually easier than people think. You pick a coverage amount. You answer some questions. You send your details in to be reviewed. Some people need a medical exam, but many do not.
The insurer checks your medical history, age, if you smoke, and your lifestyle before they offer you an insurance policy. Some providers can move fast online. After you apply, it is good to know what questions you may get and what happens next.
Insurance companies ask questions because they need to figure out the risk. This process is called underwriting. It is not the same as health insurance, but it does depend on your health and what you do.
You might get questions about:
Some people will need a medical exam, and this is often done at home. Others may not need one. Most fully underwritten policies have more questions, but they can cost less if you are healthy. It is important to answer all the questions honestly. If something big is left out or wrong, problems could come up later if you need to make a claim.
Canadians usually see two broad paths: standard coverage with more underwriting, or a policy with fewer health questions. A no medical exam option may help if you want a simpler process, but it can cost more.

A term life insurance policy is often the most practical place to start. Permanent insurance is available too, but it usually costs more. The right fit depends on health, budget, and how much coverage you want.
Once you send in your application, the insurance company looks it over. This can take a short period of time. It could also take longer if they need more details. If everything is okay and they approve you, you will look at the offer, pick who should get the money, and pay the first premium.
Some policies give you temporary coverage while your application is still in process. This depends on the insurance company and their rules. For every policy in Canada, there's a free-look period. That time lasts at least 10 days. It lets you cancel and get a refund if you want.
After your policy starts, keep your papers in a safe spot. Let your beneficiaries know where they can find the policy info and claim form. This simple step helps them if there is ever a need for a payout.
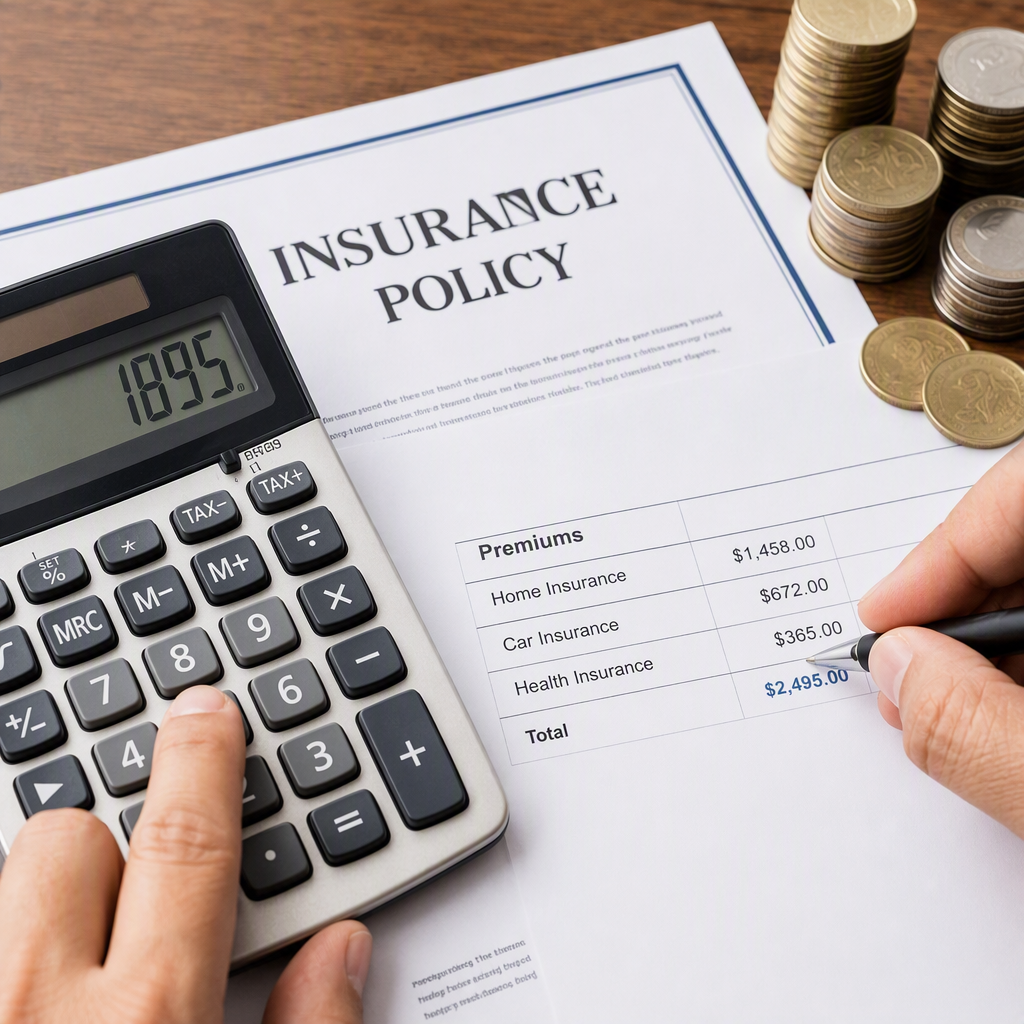
Life insurance premiums in Canada depend on risk and how the policy is set up. This means the insurer looks at how likely they are to pay money for a claim. That helps them decide the price for your insurance coverage.
People who are young and in good health often get lower premiums for their life insurance. Term life insurance is often cheaper than plans that last your whole life. The price you pay will also go up or down if you smoke, how you live, and how much coverage you pick. There are a few things that change the cost and things that can happen if you stop your payments.
Several things make life insurance premiums go up or down. Age is a big part of it. Health counts too, so some people need to take a medical exam. Smoking, hobbies that can be risky, and jobs that can be unsafe can also make the cost higher.
Rates can change because of:
Term policies often have lower premiums because they are for a set period of time. Permanent life insurance costs more since it can last for life and may give a cash value. This is important when you compare term vs whole life insurance in Canada.
Your policy will stay in place if you pay what is owed. The insurance company lets you pay each month or each year. If you miss a payment, you still get about 30 days as a grace period before your coverage stops.
If you do not pay on time:
So, how much you can pay matters right from the beginning. Picking a policy with lower premiums can help you keep it for a long time. If your budget changes, talk to your insurance company first before your policy ends. Losing coverage at the wrong time can leave you without help when you need it most.
You can’t set every price, but you can choose wisely. Many people in Canada get lower premiums by signing up early, picking only what they need, and getting term insurance.
Ways to keep costs down:
For some families, a fully underwritten policy can cost less than no-medical options. This means you have to answer more questions and maybe have a medical exam. If you want an easy way to compare life insurance in Canada, Policy Ninja can help.
A life insurance policy Canada gives one main promise. It gives money if the insured person dies while their insurance policy is active. The coverage amount is the number listed in the contract.
What your family gets depends on the type of policy you pick. Some life insurance plans pay only the death benefit. Others, like many permanent life insurance options, can build cash value. This helps you see what life insurance covers, how much it gives, and if the benefits can help while you are still living.
Life insurance does not pay one bill. Instead, it gives a death benefit. The people who get this money can use it for many things. This is a big reason life insurance benefits Canada are so helpful.
Some common uses are:
This is why life insurance coverage Canada can help young families and older adults. Some want insurance coverage for needs right now. Others want life insurance to help with estate planning or final expenses for their whole life. The main goal is to give the people you care about money when they really need it.
Your family gets the full coverage amount shown in the life insurance policy if the claim is good and the insurance policy is active. They get this payment as a free lump sum with no tax.
The amount they get is based on:
If your life insurance policy says $500,000, it will most likely be that amount paid. This free lump sum can be used by the person who gets it in any way they want. They can use it for income, debt, housing, or other needs. It can also be used for plans in the future. That’s why it is important to pick the right coverage amount before you buy life insurance.
Some life insurance policies can give you something while you are still alive, but not all do. Term life is made to give a death benefit later. Whole life and universal life insurance can build cash value as time goes on.
Possible living benefits include:
Universal life insurance is permanent coverage. It has an investment-like part that changes based on how it performs. These things help in special cases, but they also make life insurance cost more and be harder to understand. Not everyone needs them.
There are two main types of life insurance in Canada: term life and permanent life insurance. A lot of people start by looking at these because the cost, length, and what you get are not the same.
Term life insurance covers you for a set time. Permanent life insurance can cover you for your whole life as long as you keep paying for it. Inside permanent coverage, you can choose between whole life insurance and universal life. Here's what happens with each one.
Term life insurance in Canada gives you coverage for a set period of time like 10, 20, or 30 years. If you die during this period, the insurance policy pays your loved ones. If you live past this time, your coverage will stop unless you decide to renew or change it to another policy.
Many people choose term life insurance because:
For most people in Canada, term life is a good way to start your life insurance journey. It fits needs that last for just a few years and often gives you the most value for your money. If you are looking at different personal life insurance policy options, term life is usually the first thing you should go over with your insurance company or an online platform.
Permanent life insurance Canada gives you lifelong coverage. If you keep paying your premiums, the policy can stay active for your whole life. This works well for final expenses or estate needs.
It may be a good choice because it gives you:
Still, it costs more than term life insurance. Because of that, people often choose it for long-term goals and not just basic family needs. Term to 100 life insurance Canada is another permanent option that some Canadians pick when they want lifelong coverage.
Keywords used: cash value, death benefit, permanent life insurance, life insurance, lifelong coverage, guaranteed cash value, final expenses, permanent coverage, entire life
Whole life insurance gives lifelong coverage and brings more stability. The premiums stay the same, and the policy builds guaranteed cash value as time goes on. Whole life is a type of permanent life insurance.
Universal life insurance also offers lifelong coverage. It gives you more flexibility and some features that work like investments. It can be good for people who want to have more control, but you may need to pay more attention to it over time.
You may hear some business terms, like executive life insurance Canada, corporate owned life insurance Canada, partnership life insurance Canada, buy sell life insurance Canada, buy sell agreement insurance Canada, business succession insurance Canada, shareholder protection insurance Canada, business continuation insurance Canada, or what is key person insurance. These are for business needs, and not for basic family coverage.
A payout is good if the right person gets it without trouble. That is why their details matter so much in a life insurance policy. The insurance company goes by the names you list in your contract.
When the person with the life insurance dies, the people named in the insurance policy send in a death certificate and a claim form. If all things are correct, the insurance company pays the lump sum. The last two parts will tell you who to pick as beneficiaries and how to file a claim in Canada.
You can choose your spouse, child, another family member, a trust, a charity, or your estate to be the beneficiary of your life insurance policy. You may also decide to split the money between more than one person. This should fit with your financial plan.
Good planning for your insurance policy means you should:
This supports estate planning, since paying directly from a life insurance policy often helps the money skip the estate process. If you don’t know who to pick as a beneficiary, think about your goals first. You can quickly search “life insurance broker near me,” or use an online service to compare options and make life insurance easier.
To claim a life insurance payout in Canada, the person who gets the money needs to call the insurance company. They will need to ask for the claim package. The process is easy if you have all the documents and the policy is still active.
Most claims need:
The insurance company looks at your file. If the claim gets approved, they send you a lump sum. The period of time can be different. Some claims get paid in weeks, but if things are more complex, it can take longer. If you want things to go well from the start, you can compare life insurance Canada plans and get life insurance quotes Canada.
To sum up, knowing how life insurance works in Canada is important. It helps you make good choices to keep your loved ones safe and protect your money in the future. If you understand the basics like coverage, premiums, and who gets the money, you can pick a life insurance policy that fits your needs. Be sure to look at your insurance policy often. Life can change, and you want the right coverage at all times. If you want to find a life insurance policy that suits you, try comparing options with PolicyNinja and get a quote today!
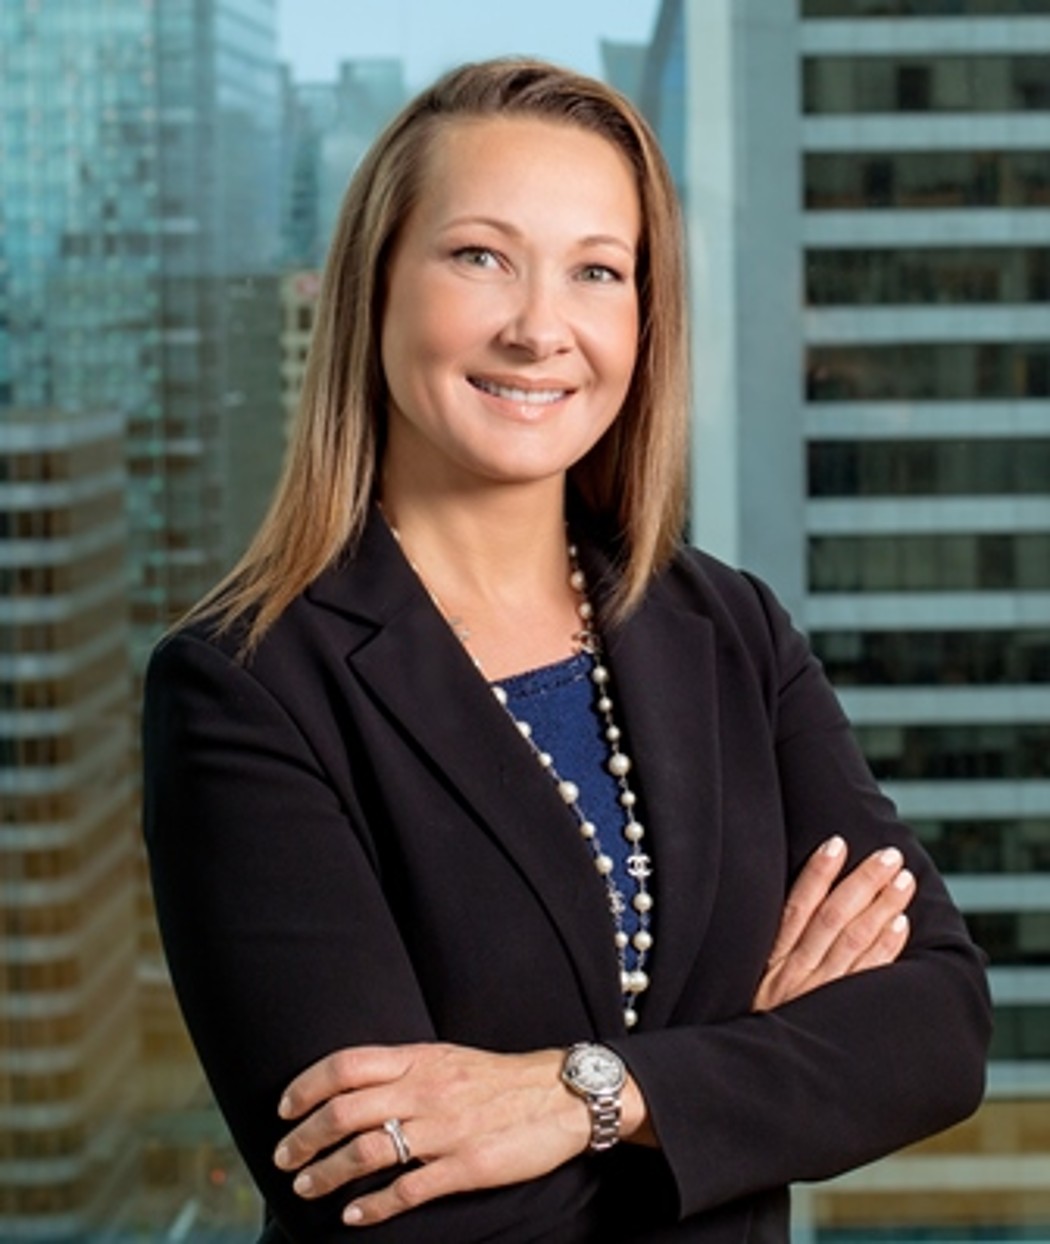
Cindy David, CFP, CLU, FEA, TEP, is President & Estate Planning Advisor at Cindy David Financial Group Ltd. in Vancouver. A recognized leader in wealth management and estate planning, Cindy guides clients with strategic, tax-effective solutions while championing innovation and women’s leadership in the financial industry. She is the former Chair of the Conference for Advanced Life Underwriting (CALU) — Canada’s professional association for senior life insurance and financial advisors that advances education, advocacy, and best practices in advanced planning and public policy.


